Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- How to Evaluate Spark Plug Suppliers for Consistent Quality and Lead TimesSpark plugs supplier evaluation guide: compare quality control, traceability, fitment, total cost, and reliable lead times to secure dependable engine maintenance supply.
- What Drives System Interoperability Testing Service Costs in Complex Projects?System interoperability testing service cost depends on integration scope, workflows, environments, and assurance needs. Learn how to budget smarter and reduce project risk.
- Project Planning Sourcing Guides: How to Qualify Suppliers Before Work StartsSourcing guides project planning helps teams qualify suppliers before work begins—verify compliance, delivery capacity, financial strength, and sustainability to reduce risk and protect project outcomes.
Popular Tags
TerraVista Metrics (TVM)Industry NewsBrent Crude Drops >4% on US-Iran Talks: Cost Relief for Kinetic Art & Cableway Tech Suppliers
auth.Time
Oct 07, 2026Click Count
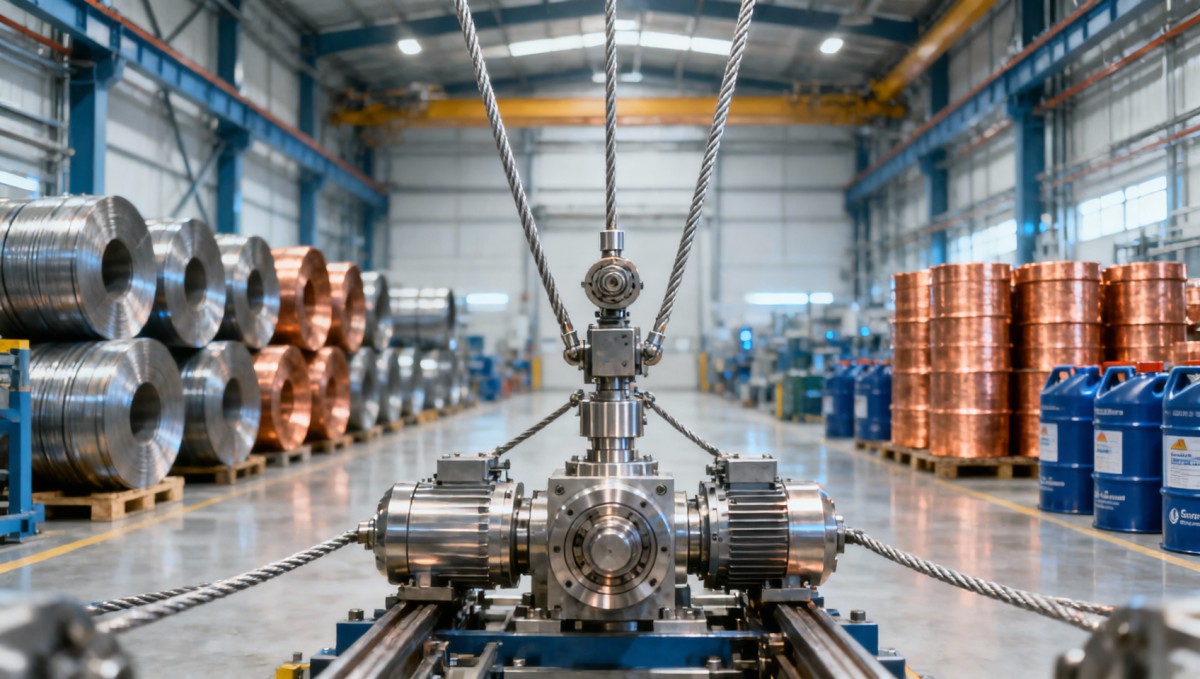
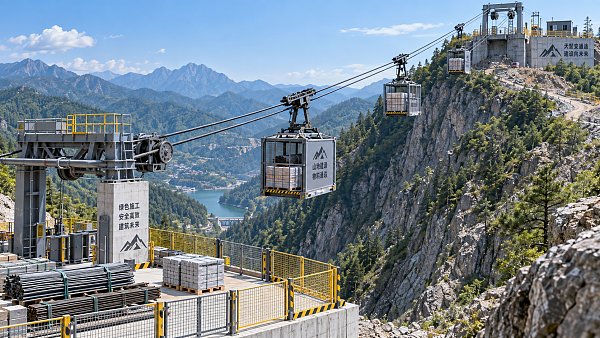
On May 25, 2026, rising expectations of a US–Iran agreement triggered a >4% single-day decline in Brent crude oil prices—the sharpest drop in two weeks—impacting cost structures across energy-sensitive industrial supply chains, particularly for Kinetic Art (drive motors/bearings) and Cableway Tech (haul ropes/tensioning systems) manufacturers and suppliers.
Confirmed Market Movement
On May 25, 2026, Brent crude fell more than 4% in a single trading session, reaching a two-week low. This price correction was directly attributed to heightened diplomatic optimism surrounding US–Iran negotiations. As steel, copper, and synthetic lubricants—key raw materials for Kinetic Art and Cableway Tech components—exhibit strong correlation with energy input costs, their procurement pressure eased accordingly. Concurrently, Chinese suppliers reported expanded pricing flexibility in quotations for these materials.
Supply Chain Impact by Role
Direct Trading Enterprises
These firms face revised margin dynamics due to lower landed costs for base metals and specialty chemicals. Their exposure lies primarily in inventory valuation timing and forward contract renegotiation windows—especially for contracts indexed to energy-linked benchmarks or metal spot indices.
Raw Material Procurement Entities
Purchasing departments managing long-term agreements for steel billets, electrolytic copper cathodes, or PAO-based synthetic lubricants may now revisit pricing clauses, escalation mechanisms, and minimum order volumes—particularly where contracts include energy-cost pass-through provisions.
Manufacturing Firms
For producers of drive motors, bearing assemblies, traction cables, and hydraulic tensioners, reduced input volatility supports more predictable production costing and improved quoting accuracy for OEM tenders—especially those requiring strict cost-of-goods-sold disclosure.
Supply Chain Service Providers
Logistics coordinators, customs brokers, and certification support agencies should anticipate increased demand for expedited documentation handling—including material origin declarations, RoHS/REACH compliance dossiers, and lubricant formulation safety data sheets—given tighter quoting cycles following cost relief.
Strategic Priorities for Enterprises
Review Raw Material Sourcing Terms
Assess existing procurement contracts for energy-indexed pricing clauses, review supplier MOQs and lead time buffers, and evaluate opportunities to lock in favorable rates for copper, cold-rolled steel, and synthetic lubricants ahead of potential market stabilization.
Validate Technical Documentation Alignment
Ensure that lubricant specifications (e.g., ISO VG 46, DIN 51509 Type II), bearing metallurgy certifications (e.g., ASTM A295, EN 10088), and cable tensile test reports comply with latest tender requirements—particularly where bid submissions reference updated material cost assumptions.
Update Supplier Qualification Files
Reconfirm that key Chinese suppliers maintain valid ISO 9001, ISO 14001, and relevant industry-specific approvals (e.g., ISO 16840 for wire rope, API RP 9B for lifting equipment)—as procurement teams increasingly link cost flexibility with verified compliance capacity.
Monitor Tender Timeline Adjustments
Track whether infrastructure and transit system tenders—especially those referencing Kinetic Art or Cableway Tech subsystems—are shortening technical evaluation windows or adjusting life-cycle cost calculation models in response to lower projected material inflation.
Industry Perspective: Beyond Short-Term Cost Relief
Analysis shows this price correction is not merely cyclical—it reflects recalibrated risk premiums in global commodity markets, which in turn influence how procurement rules are applied across international infrastructure projects. From an industry perspective, what deserves closer attention is the growing linkage between geopolitical negotiation timelines and tender evaluation criteria: more buyers are embedding ‘raw material cost stability’ as a de facto technical scoring factor—not just a commercial one. It is more appropriate to understand this as an emerging soft requirement in technical bid alignment, especially for multi-year delivery contracts where total cost of ownership remains central.
Key Takeaway for Stakeholders
This event underscores how macro-level diplomatic developments can rapidly reshape micro-level procurement economics—without new regulations or formal policy changes. For Kinetic Art and Cableway Tech stakeholders, the immediate benefit lies in enhanced quotation agility; the longer-term implication is a tightening of expectations around documentation rigor, supply chain transparency, and lifecycle cost modeling in competitive bidding processes.
Source Attribution
This article was generated exclusively from the user-provided title, event timestamp (2026-05-25T00:00:00+08:00), and summary. Specific official source links were not provided in the input and should be verified continuously. Ongoing monitoring is advised for updates to tender documentation templates, national procurement guidelines, industry association advisories (e.g., ISO/TC 100, CEN/TC 378), and regional customs tariff interpretations related to component classification.
Recommended News
 Oct 10, 2026How to Evaluate Spark Plug Suppliers for Consistent Quality and Lead TimesSpark plugs supplier evaluation guide: compare quality control, traceability, fitment, total cost, and reliable lead times to secure dependable engine maintenance supply.
 Oct 08, 2026What Drives System Interoperability Testing Service Costs in Complex Projects?System interoperability testing service cost depends on integration scope, workflows, environments, and assurance needs. Learn how to budget smarter and reduce project risk.
 Oct 07, 2026Project Planning Sourcing Guides: How to Qualify Suppliers Before Work StartsSourcing guides project planning helps teams qualify suppliers before work begins—verify compliance, delivery capacity, financial strength, and sustainability to reduce risk and protect project outcomes.
 Oct 06, 2026Buyer’s Guide to Kinetic Art: Choosing Safe, Durable Pieces for Public SpacesBuyer guides kinetic art for public spaces: learn how to choose safe, durable, low-maintenance installations with reliable engineering, materials, controls, and lifecycle value.
 Oct 05, 2026Regulatory Compliance Vendor Comparison: How to Assess Audit Readiness and RiskRegulatory compliance vendor comparison made practical: assess audit readiness, evidence quality, change control, and supply-chain risk before award. Learn how to choose defensible suppliers.
 Oct 04, 2026A Procurement Checklist for Tourism Hardware Equipment in Resorts and Visitor CentersTourism hardware equipment procurement checklist for resorts and visitor centers: compare durability, compliance, lifecycle costs, supplier support, and logistics.
 Oct 03, 2026Verified Performance Certification: What It Proves During Product QualificationVerified performance certification helps teams qualify products with confidence. Learn how to assess scope, test conditions, and delivery controls before approval.
 Oct 02, 2026North American Yacht Tech: Market Shifts Reshaping Retrofit and New-Build DemandYacht tech North America is reshaping retrofit and new-build choices. Explore smarter energy, connectivity, cybersecurity, and lifecycle strategies for lasting yacht value.
 Oct 01, 2026Multiaxial Material Fatigue Analysis for Predicting Service Life Under Variable LoadsMultiaxial material fatigue analysis helps predict service life under variable loads, enabling safer procurement, lower lifecycle risk, and durable tourism infrastructure.
 Sep 30, 2026How RV Dealers Can Vet Wholesale Accessory Distributors for Reliable StockRV accessories wholesale distributor vetting guide for dealers: verify stock, fitment, fulfillment, terms, and support to reduce delays and protect margins.
 Sep 29, 2026When Does a Cableway System Upgrade Improve Capacity and Reduce Downtime?Discover when a cableway systems upgrade can increase real capacity, cut unplanned downtime, and deliver a stronger lifecycle return for tourism operations.
 Sep 28, 2026What Does Tourism Destination Infrastructure Cost? A Budgeting Guide for DevelopersTourism destination infrastructure price guide for developers: budget utilities, systems, installation, lifecycle costs, and contingencies for smarter investments.
 Sep 27, 2026How to Design Scalable System Integration Testing for Multi-Vendor DeploymentsScalable system integration testing for multi-vendor deployments: build resilient, secure, and growth-ready operations with proven interface, resilience, and acceptance strategies.
 Sep 26, 2026Regulatory Compliance Procurement Support: How to Vet Suppliers Before Contract AwardRegulatory compliance procurement support helps buyers vet suppliers, verify evidence, manage risks, and secure compliant assets before contract award.
 Sep 25, 2026Resort System Integration: How to Connect PMS, Guestroom Controls, and KiosksResort system integration guide: connect PMS, guestroom controls, and kiosks with reliable workflows, secure data, and seamless guest experiences.
 Sep 24, 2026Hotel Tourism Benchmarking: Which KPIs Reveal Competitive Market Position?Tourism benchmarking for hotels reveals the KPIs that define competitive position, from RevPAR index and demand quality to profit, guest experience, and asset resilience.
 Sep 23, 2026Planning Smart Classroom Solutions for Hybrid Learning Without Creating AV Support GapsSmart classroom solutions for reliable hybrid learning: standardize workflows, strengthen AV support, and deliver seamless teaching experiences.
 Sep 22, 2026Industrial Compressors: How to Size Air Capacity and Pressure for Factory DemandIndustrial compressors sizing guide: calculate factory air capacity, end-use pressure, peak demand, receiver storage, leakage, and energy-efficient system performance.
 Sep 21, 2026What Do Eco-Lodging Standards Cost, From Certification Fees to Compliance Upgrades?Eco lodging standards cost explained: compare certification fees, compliance upgrades, documentation, and operational investments to budget smarter and avoid costly rework.
 Sep 20, 2026Supply Chain Analysis: How to Identify Cost, Risk, and Lead-Time BottlenecksSupply chain analysis helps tourism project leaders uncover cost, risk, and lead-time bottlenecks—protecting opening dates, budgets, and guest-ready operations.
 Sep 19, 2026How to Choose Industry Benchmarking Tools That Deliver Actionable Performance InsightsIndustry benchmarking tools: learn how to validate data, compare lifecycle costs, assess compliance, and turn performance evidence into smarter decisions.
 Sep 18, 2026Technical Procurement in Southeast Asia: Evaluating Suppliers, Compliance, and Lead TimesTechnical procurement Southeast Asia: evaluate suppliers, compliance, lead times, and total cost to secure reliable, project-ready assets. Read the practical guide.
 Sep 17, 2026Glamping Site Supplier Selection: A Checklist for Quality, Lead Times, and SupportGlamping site supplier selection made simple: assess quality, lead-time reliability, installation readiness, and after-sales support for a resilient, profitable site.
 Sep 16, 2026How to Plan a Slope Access Cable Transport System for Steep-Site ConstructionSlope access cable transport planning for steep-site construction: evaluate loads, terrain, terminals, safety, weather risks, and costs for reliable low-impact logistics.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.