Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- How to Plan Outdoor Kinetic Art Installations for Parks, Resorts, and Public SpacesOutdoor kinetic art planning guide for parks, resorts, and public spaces—explore safety, engineering, materials, lifecycle costs, and maintenance for lasting visitor impact.
- Amusement Equipment Testing for Family Entertainment Centers: Key Safety ChecksAmusement equipment testing for family entertainment centers: discover essential safety checks for restraints, brakes, interlocks, structural wear, and daily operations.
- What Engineering Performance Testing Should Cover During a Specification ReviewEngineering performance testing for specification review: learn how to verify structural strength, durability, safety, sustainability, and system reliability before costly project decisions.
Popular Tags
TerraVista Metrics (TVM)Industry NewsIndustry Insights for Market Expansion: How to Identify High-Potential Regions?
auth.Time
Sep 05, 2026Click Count
Industry Insights for Market Expansion: How to Identify High-Potential Regions?
Successful expansion now depends less on headline growth rates and more on whether demand, infrastructure, and regulatory readiness are arriving at the same time. That sounds obvious, but in tourism-linked sectors it is where many market entry decisions still go wrong. A region can show strong visitor growth and still be a poor expansion target if grid reliability is weak, local compliance is fragmented, or procurement cycles are too slow to support asset-heavy development. The most useful industry insights for market expansion come from reading these signals together rather than treating them as separate workstreams.
This matters even more in 2026 planning, when tourism investment is being shaped by two forces that do not always move in lockstep. One is the return of physical destination development: modular lodging, attraction upgrades, outdoor infrastructure, hotel digitization, and refurbishment of aging hospitality assets. The other is a harder investment climate, where financing costs, supply chain concentration, and tighter scrutiny of technical performance have made investors less tolerant of optimistic assumptions. Regions that look promising on a tourism map may still fail the capital discipline test.
The market is rewarding operational readiness, not just visitor potential
One of the clearest shifts across tourism development is that operators and developers are no longer evaluating expansion regions purely through destination appeal or projected arrivals. They are looking for environments where assets can be deployed, maintained, insured, and upgraded with fewer surprises. In practical terms, that puts more weight on customs reliability, local installer capability, access to certified components, energy stability, digital connectivity, and clarity around environmental permitting.
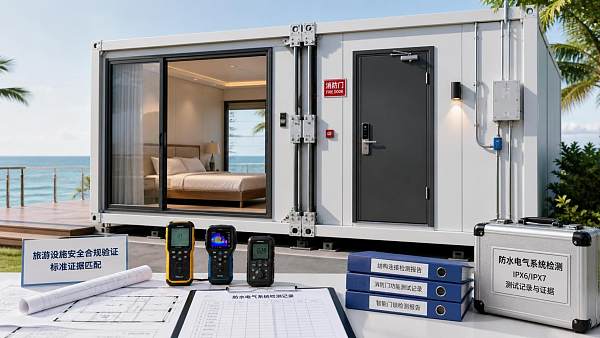
This is particularly visible in segments such as prefabricated eco-structures and smart hotel systems. A modular cabin project may appear commercially viable in a remote high-growth destination, but transport constraints, climate exposure, and local code interpretation can alter the cost curve quickly. Likewise, hotel automation projects are far easier to scale in regions where connectivity standards, cybersecurity expectations, and systems integration talent are already established. Expansion teams that treat technical deployment conditions as a late-stage detail are increasingly paying for that mistake.
The implication is straightforward: high-potential regions are no longer simply the places with rising tourism demand. They are the places where demand is becoming buildable.
Why secondary markets deserve closer attention
A decade ago, market expansion conversations often centered on major gateway cities and well-known resort corridors. That logic is weakening. Secondary regions, especially those benefiting from domestic tourism growth, infrastructure decentralization, or public investment in transport and utilities, are increasingly attractive because they offer a better balance between land economics, asset differentiation, and operational scalability.
That does not mean every secondary market is ready. Some are gaining visibility faster than they are gaining technical capacity. But where public infrastructure is keeping pace, these regions can be more forgiving for new formats such as glamping, hybrid leisure-retail sites, nature-based stays, and mid-scale tech-enabled hospitality. They also tend to be more receptive to modular construction and standardized procurement models, partly because these approaches reduce construction complexity in places with thinner contractor depth.
For companies tracking expansion, the useful question is not whether a market is primary or secondary. It is whether the region shows coordinated growth across transport access, utilities, labor availability, site readiness, and local policy support. When those pieces align, the cost of execution often matters more than the prestige of the location.
Standards and compliance are becoming market signals in their own right
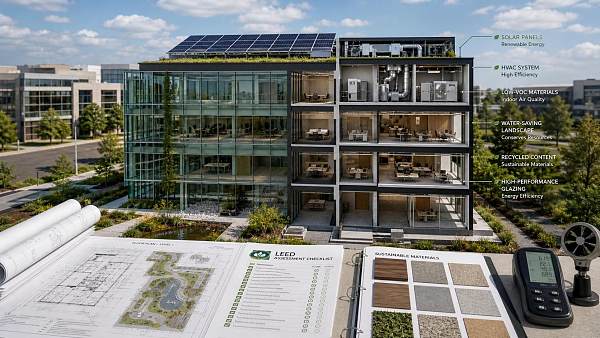
A quieter but more consequential change is the growing role of standards, testing requirements, and compliance expectations in region selection. In tourism infrastructure, expansion used to be discussed as a commercial exercise first and a compliance exercise later. That order has flipped in many categories. Energy performance expectations, fire safety requirements, digital security controls, material traceability, and environmental disclosure are now shaping procurement at the front end.
For decision-makers, this creates a useful screening lens. Regions with more mature regulatory frameworks can be slower to enter, but they often provide greater long-term clarity. Markets with unclear enforcement or inconsistent local interpretation may look flexible in the short run, yet they introduce downstream risk around retrofits, operational downtime, insurance, and reputational exposure. In other words, regulatory friction is not always a reason to avoid a region; sometimes it is evidence that the market is institutionalizing.
This is where firms such as TerraVista Metrics become relevant beyond certification. Benchmarking technical performance and comparing sourcing options across jurisdictions helps expansion teams distinguish between a market that is genuinely ready and one that is merely permissive. That distinction is easy to miss when commercial teams are under pressure to secure pipeline growth.
Supply chain structure now tells you almost as much as customer demand
Another strong signal in current market expansion analysis is supply chain depth. The issue is no longer just lead time. It is dependency. Regions that rely on narrow supplier bases for building systems, hospitality furnishings, amusement hardware, or outdoor equipment may remain exposed to disruptions even when final demand looks healthy. For asset-heavy tourism projects, that exposure affects opening schedules, maintenance costs, and the ability to replace components without redesign.
The smarter expansion models now test three questions early. Can core components be sourced through more than one qualified channel? Is there regional service support after installation? And can the local market absorb future upgrades without rebuilding the entire technical stack? These questions are especially important for smart hotel systems, where interoperability matters as much as device quality, and for attractions infrastructure, where downtime carries both revenue and safety consequences.
Markets with improving logistics, maturing local assembly capacity, and stronger alignment between imported systems and local servicing ecosystems are gaining an advantage. Not because they are the cheapest, but because they reduce the probability of expensive operational discontinuity.
A practical way to read regional potential
Executives do not need a perfect forecasting model to compare regions. They need a disciplined way to separate visible growth from durable investability. The most reliable signals usually come from combinations rather than single indicators.
No single row in that table is enough on its own. But when several appear together, the regional picture becomes clearer. Markets worth prioritizing tend to show evidence of coordination: infrastructure upgrades, rising technical expectations, and buyers who are learning to value lifecycle performance over initial price.
What is changing inside procurement behavior
One underappreciated reason some regions are becoming more attractive is the changing behavior of procurement teams themselves. In many tourism-related projects, procurement used to be downstream from concept development. Now it often shapes the commercial model from the beginning. Buyers are asking harder questions about durability under heavy usage, replacement cycles, interoperability, carbon-related documentation, and maintenance burdens. That shift favors regions where suppliers can provide verified performance data and where asset owners have enough technical literacy to use it.
This is especially relevant across hospitality furnishing and outdoor leisure infrastructure. A market that is expanding quickly but remains fixated on lowest acquisition cost may produce short project pipelines and weak aftersales economics. By contrast, a region where developers and operators are comparing materials, warranty conditions, service networks, and compliance documentation often supports more stable long-term positioning. Mature demand is not always larger demand, but it is often easier to build around.
Where caution is still warranted
There is a temptation to read every tourism rebound, airport expansion, or smart-city initiative as a green light for market entry. That is not how risk behaves in this cycle. Some regions are producing impressive top-line tourism narratives while still showing weak fundamentals for sustained deployment: inconsistent grid performance, unclear approvals for modular construction, limited service ecosystems for connected hotel technology, or exposure to volatile import regimes. These are not theoretical issues. They affect commissioning schedules, lifecycle cost, and the credibility of financial projections.
A second caution concerns over-standardization. Companies expanding across regions often assume a successful asset model can be replicated with minimal adjustment. In reality, climate loads, guest usage patterns, labor constraints, and local code interpretations can alter what “best practice” looks like. The more technical the asset, the less useful a copy-paste approach becomes. Expansion discipline now requires regional adaptation without losing the efficiencies of standardization.
The regions most likely to outperform are the ones becoming easier to trust
That may be the most useful way to frame the next phase of market selection. High-potential regions are not simply those attracting travelers or announcing investment plans. They are the ones becoming easier to underwrite because more elements of the operating environment can be tested, benchmarked, and verified. Trust, in this context, is practical: reliable inputs, clearer standards, qualified servicing capacity, and demand that can support quality-driven procurement.
For decision-makers, the next twelve to eighteen months will likely reward a narrower but more evidence-based expansion lens. Watch where tourism demand is being matched by infrastructure deployment, not merely promoted by destination branding. Watch where technical compliance is becoming more legible, even if the process is stricter. Watch where procurement teams are moving from aesthetic selection to performance validation. Those are usually the early signs that a region is not just growing, but becoming investable at scale.
In that environment, the most valuable industry insights for market expansion will come from combining market demand signals with engineering reality. That is where weaker expansion stories tend to unravel, and where stronger regional bets start to stand out.
Recommended News
 Sep 01, 2026How to Use a Tourism Standards Database to Verify Safety and Compliance RequirementsTourism standards database guide: verify safety, compliance, evidence scope, test conditions, and jurisdiction requirements with confidence.
 Aug 31, 2026Material Performance Validation: Tests and Acceptance Criteria for Critical PartsMaterial performance validation: discover essential tests and acceptance criteria that help critical parts withstand loads, corrosion, fatigue, and real-world service conditions.
 Aug 26, 2026What Is a CMS and How Do You Choose One for a Growing Business Website?CMS explained for growing business websites: learn how to choose a CMS that supports SEO, workflows, integrations, and long-term scalability without costly rebuilds.
 Aug 24, 2026How to Build a Technical Procurement Content Workflow for Faster Vendor EvaluationTechnical procurement content workflow strategies for faster vendor evaluation: standardize intake, compare evidence clearly, surface risks early, and cut costly procurement delays.
 Aug 20, 2026How to Evaluate Sustainable Concrete Alternatives for Low-Carbon Building ProjectsSustainable concrete alternatives: learn how to compare carbon data, structural performance, code compliance, and supply risk to choose low-carbon concrete solutions with confidence.
 Aug 17, 2026What Does Product Category Insights Reveal About Buyer Demand and Market Positioning?Product category insights reveal buyer demand, key product attributes, and market positioning. Learn how to spot reliable signals, compare segments, and make smarter decisions.
 Aug 13, 2026How to Use Industry Benchmarking to Improve Specification Planning DecisionsIndustry benchmarking for specification planning helps technical evaluators make smarter procurement decisions, reduce risk, and improve long-term performance with evidence-based standards.
 Aug 12, 2026Technical Certification Pricing Model: What Drives Cost and How to Compare QuotesTechnical certification pricing model explained: learn what drives cost, spot hidden risks in low quotes, and compare certification proposals with confidence before you approve budget.
 Aug 09, 2026How to Evaluate Tourism Equipment for Eco Resorts Without Compromising Guest ExperienceTourism equipment evaluation for eco resorts made practical: learn how to balance sustainability, durability, and guest comfort to avoid costly mistakes and choose smarter.
 Aug 07, 2026How to Evaluate LEED Standards for Environmental Sustainability in Building ProjectsEnvironmental sustainability assessment LEED standards explained: learn how to evaluate prerequisites, credits, costs, and project risks to achieve smarter, more reliable green building outcomes.
 Aug 05, 2026Why Eco Structures in the Middle East Are Shifting Toward Modular, Off-Grid DesignsEco structures in Middle East markets are moving to modular, off-grid designs for faster delivery, lower operating risk, and stronger climate resilience. Discover what is driving the shift.
 Jul 30, 2026Industry Insights for Market Expansion: How to Identify High-Potential Regions?Industry insights for market expansion: learn how to identify high-potential regions by assessing demand, infrastructure, compliance, and supply chain readiness for smarter growth.
 Jul 14, 2026How to Apply a Tourism Innovation Validation Framework to Assess New Visitor ProjectsTourism innovation validation framework explained: learn how to assess new visitor projects, reduce delivery risk, verify compliance, and make smarter investment decisions.
 Jul 13, 2026Import Market Research Checklist: How to Assess Demand, Tariffs, and Supplier RiskImport market research made practical: learn how to assess real demand, model tariffs, and reduce supplier risk with a clear checklist for smarter sourcing decisions.
 Jul 11, 2026Fade Resistant Durability: Which Test Methods Matter for Long-Term Outdoor Use?Fade resistant durability starts with the right test data. Discover which methods best predict long-term outdoor performance, color stability, and lower lifecycle risk.
 Jul 09, 2026Electronic Gadgets for Travel and Daily Use: How to Pick Features That MatterElectronic gadgets for travel and daily use should deliver real value. Learn how to compare battery life, portability, durability, and connectivity before you buy.
 Jul 08, 2026Regulatory Compliance Framework Explained: Core Elements, Gaps, and Audit ReadinessRegulatory compliance framework explained for modern organizations: learn core elements, common gaps, and audit readiness strategies to reduce risk, improve control, and strengthen decisions.
![]() Jul 07, 2026Faucets and Mixers Buying Guide: Types, Valve Options, and Finish SelectionFaucets and mixers buying guide covering fixture types, valve options, and finish selection. Compare durability, comfort, maintenance, and performance before you buy.
 Jul 06, 2026Tourism Equipment Specification Review: Which Ratings Matter Before You Buy?Tourism equipment specification review made practical: learn which ratings truly affect safety, lifecycle cost, compliance, and uptime before you choose a supplier.
 Jul 05, 2026What Is Material Fatigue in Composites? Failure Mechanisms and Service Life BasicsMaterial fatigue composites explained: learn key failure mechanisms, service life factors, and how to assess durability risks before specifying composite products.
 Jul 03, 2026Tourism Destination Infrastructure in North America: What Investors and Developers Evaluate FirstTourism destination infrastructure in North America shapes returns from day one. Discover what investors and developers assess first to reduce risk, improve resilience, and protect long-term value.
 Jul 02, 2026Tourism Development Validation Methodology Explained: Metrics, Data Sources, and Use CasesTourism development validation methodology explained with key metrics, trusted data sources, and real use cases to reduce risk, improve compliance, and guide smarter tourism investment decisions.
 Jun 30, 2026Regulatory Compliance Criteria Explained: How to Evaluate Requirements by Product and MarketRegulatory compliance criteria explained clearly: learn how to assess product and market requirements, reduce approval risk, and make smarter sourcing and market-entry decisions.
 Jun 29, 2026Efficient Procurement Planning: How to Reduce Delays and Control Budget RiskEfficient procurement planning helps reduce delays, control budget risk, and improve supplier decisions with data-driven strategies for stronger project delivery.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.