Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- How to Evaluate Spark Plug Suppliers for Consistent Quality and Lead TimesSpark plugs supplier evaluation guide: compare quality control, traceability, fitment, total cost, and reliable lead times to secure dependable engine maintenance supply.
- What Drives System Interoperability Testing Service Costs in Complex Projects?System interoperability testing service cost depends on integration scope, workflows, environments, and assurance needs. Learn how to budget smarter and reduce project risk.
- Project Planning Sourcing Guides: How to Qualify Suppliers Before Work StartsSourcing guides project planning helps teams qualify suppliers before work begins—verify compliance, delivery capacity, financial strength, and sustainability to reduce risk and protect project outcomes.
Popular Tags
TerraVista Metrics (TVM)Industry NewsSolar water heaters still make sense in these building types
auth.Time
Oct 07, 2026Click Count
For enterprise decision-makers balancing energy costs, carbon targets, and long-term asset performance, solar water heaters still deserve serious attention. In building types where hot water demand is stable and operational efficiency matters, this technology can deliver measurable returns. Understanding where solar water heaters make the most sense helps developers, hotel operators, and infrastructure planners invest with greater confidence and precision.
Why the discussion around solar water heaters is changing again
In many markets, solar water heaters were once treated as a legacy sustainability option: useful, but overshadowed by heat pumps, smart controls, and full-building electrification strategies. That view is shifting. The reason is not that older technology suddenly became fashionable, but that the economics of thermal demand are being re-examined building by building. For facilities with predictable hot water loads, the direct capture of solar heat can still outperform more complex alternatives on lifecycle efficiency, maintenance simplicity, and resilience.
This shift matters across tourism, hospitality, mixed-use development, and remote destination infrastructure. Energy procurement teams are under pressure to cut operating costs without compromising guest comfort. Sustainability leaders must show credible carbon reductions, not just aspirational roadmaps. Owners and developers also want systems that fit into phased retrofits rather than requiring a complete redesign of electrical or mechanical networks. In that context, solar water heaters are being reconsidered not as universal solutions, but as highly effective tools for the right building types.
For organizations evaluating tourism assets, hotels, eco-lodges, staff housing, wellness facilities, and service-heavy accommodation, the question is no longer whether solar thermal is modern enough. The better question is where solar water heaters align with load profile, roof conditions, carbon reporting, and asset strategy.
The strongest market signal: stable hot water demand is becoming more valuable
One of the clearest industry changes is the growing premium placed on demand predictability. Building systems that operate against stable, recurring loads are easier to optimize, finance, and benchmark. Hot water is one of the few energy uses in hospitality and tourism infrastructure that often follows a repeatable pattern. Guest rooms, communal bathing areas, kitchens, laundries, worker accommodation, and spa services create thermal demand that is easier to map than many forms of space conditioning.
That predictability is especially important as utility prices fluctuate and carbon accounting becomes more granular. When decision-makers can estimate morning peak use, seasonal occupancy, recovery times, and storage requirements, solar water heaters become easier to size and justify. Instead of being judged only on headline energy savings, they are being evaluated as part of a broader thermal management strategy.
Which building types still make the most sense
Not every asset is a strong candidate. The most suitable projects share several traits: consistent domestic hot water demand, sufficient roof or collector area, a favorable solar resource, and a facility team willing to manage storage and backup integration properly. In practice, several building types continue to stand out.
Hotels and resorts with year-round occupancy
Hotels remain one of the clearest use cases for solar water heaters, especially properties with sustained occupancy, on-site laundry, kitchens, and wellness amenities. In these settings, hot water demand is not incidental; it is operationally central. Midscale and upscale hotels in warm or mixed climates can often justify solar thermal more easily than highly seasonal properties because their demand profile supports better utilization of stored heat.
Eco-lodges, glamping sites, and remote accommodation clusters
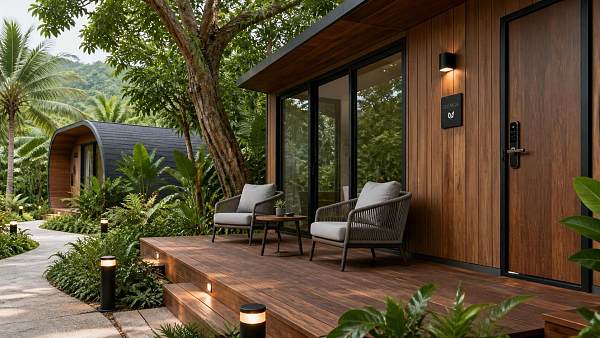
For remote hospitality formats, the value proposition extends beyond utility savings. Solar water heaters can reduce diesel dependence, simplify off-grid or weak-grid operations, and reinforce sustainability positioning that guests increasingly expect to be backed by real infrastructure choices. Where TerraVista Metrics and similar benchmarking approaches matter is in verifying collector durability, insulation performance, storage losses, and the reliability of integrated pumping or control systems under variable site conditions.
Dormitories, staff housing, and workforce accommodation
Buildings with concentrated daily shower demand are often excellent candidates. Staff housing near resorts, amusement facilities, or large tourism developments tends to have recurring peak usage and less variability than guest-facing assets. That makes system sizing more straightforward and can produce attractive long-term economics, particularly where grid power is expensive or conventional water heating depends on delivered fuel.
Wellness, spa, and aquatic support facilities
Facilities centered on bathing, treatment rooms, warm-water washing, or pool support functions usually maintain substantial thermal loads. While not every aquatic application is suitable for direct solar thermal design, solar water heaters can still offset a significant share of domestic or process-adjacent hot water demand. In premium hospitality, this becomes especially relevant because guest expectations for comfort are high, and thermal systems must perform without interruption.
Healthcare-linked hospitality and institutional lodging
Recovery centers, senior living facilities, and institutional residences attached to travel or wellness ecosystems may also benefit where hot water demand is steady and hygiene standards require dependable supply. In these cases, solar water heaters are not chosen for novelty but for long-horizon efficiency and emissions reduction when combined with robust backup systems.
Why some properties are better candidates than others
The strongest driver is load consistency. Buildings with short bursts of irregular occupancy often leave collector capacity underused. By contrast, properties with recurring morning and evening use can capture more value from thermal storage. A second driver is physical integration. Solar water heaters need viable roof space, appropriate orientation, manageable shading, and a piping route that does not create excessive heat loss or installation complexity.
The third driver is procurement maturity. More buyers now understand that collector efficiency alone does not determine success. Storage tank sizing, backup heat source coordination, controls, corrosion resistance, insulation quality, freeze protection strategy, and maintenance access all affect real-world performance. This is where a benchmarking mindset becomes essential. Enterprise buyers increasingly want engineering evidence, not brochure claims.
Where procurement priorities are moving
A notable change in the market is the move away from buying solar water heaters as isolated hardware. Procurement teams now ask how the system fits into broader building intelligence, asset monitoring, and decarbonization reporting. This is particularly visible in high-standard tourism developments, where sustainability commitments must coexist with guest experience requirements and brand-level operating procedures.
Decision-makers are increasingly focusing on five procurement questions. First, can the system deliver reliable output under the site’s occupancy pattern? Second, how well does it integrate with heat pumps, boilers, or electric backup systems? Third, what is the maintenance burden over a multiyear operating cycle? Fourth, can performance be monitored and verified? Fifth, does the supplier provide technical documentation detailed enough for engineers, consultants, and auditors?
The role of hybrid energy strategy is growing
Another important trend is that solar water heaters are increasingly specified as part of hybrid systems rather than as single-source solutions. This improves reliability and makes adoption easier in commercial settings. For example, a hotel may use solar thermal to preheat domestic hot water, with heat pumps or condensing boilers handling peak demand and low-sun periods. That kind of layered approach reduces energy use while preserving operational certainty.
This also means procurement standards are changing. Buyers no longer just compare collector types. They compare system architecture. Can controls prioritize solar gain intelligently? Can storage temperatures be maintained safely and efficiently? Is the backup source staged properly? Can the full system be expanded later if occupancy grows? These are strategic questions, especially for phased tourism developments and destination infrastructure rollouts.
Signals that solar water heaters may not be the right fit
Trend analysis is most useful when it also identifies where caution is needed. Solar water heaters may be a weaker fit for buildings with highly irregular occupancy, severe shading, limited roof area, or very low hot water demand relative to total project complexity. They may also underperform when maintenance capacity is weak or when system design ignores storage losses and circulation inefficiencies.
In premium developments, the risk is not usually the concept itself but poor integration. Oversized systems, inaccessible maintenance layouts, weak freeze protection, and unrealistic savings assumptions can undermine performance and internal confidence. That is why disciplined engineering review is more important than broad enthusiasm.
How enterprise teams should judge the next wave of opportunities
For decision-makers, the practical path forward is to treat solar water heaters as a targeted thermal asset class. Start with the building portfolio, not the product list. Identify sites with recurring hot water demand, favorable solar exposure, and meaningful fuel or electricity costs. Then compare solar thermal against alternative water heating pathways on a whole-system basis, including storage, controls, redundancy, and maintenance.
The best opportunities often emerge where three conditions overlap: hot water is mission-critical, sustainability targets are becoming more binding, and infrastructure teams want proven rather than experimental solutions. In tourism and hospitality, that combination is increasingly common. Operators are expected to decarbonize visible guest services while protecting comfort, uptime, and brand standards. Solar water heaters can support that balance when matched to the right load profile.
A practical decision framework for the coming planning cycle
Before allocating budget, enterprise teams should confirm several issues. Is annual occupancy stable enough to support useful solar contribution? Is there sufficient collector area with manageable installation logistics? Can the system integrate with existing or planned backup heat sources? Are monitoring and reporting requirements likely to increase? Does the supplier provide engineering data that supports long-term procurement confidence? These questions help separate strategic fit from superficial green positioning.
For organizations building or upgrading tourism infrastructure, the larger lesson is clear: solar water heaters still make sense, but only when evaluated through the lens of demand stability, system integration, and measurable operational value. They are no longer best understood as generic sustainability hardware. They are a selective, performance-sensitive solution for building types where hot water demand is durable, carbon pressure is real, and lifecycle efficiency matters.
If your team wants to judge whether current market changes support adoption, focus on the signals that matter most: load consistency, roof suitability, hybrid system compatibility, documentation quality, and verification capability. Those are the factors most likely to determine whether solar water heaters become a credible long-term asset for your portfolio or simply another underperforming line item.
Recommended News
 Oct 08, 2026What Drives System Interoperability Testing Service Costs in Complex Projects?System interoperability testing service cost depends on integration scope, workflows, environments, and assurance needs. Learn how to budget smarter and reduce project risk.
 Oct 03, 2026Verified Performance Certification: What It Proves During Product QualificationVerified performance certification helps teams qualify products with confidence. Learn how to assess scope, test conditions, and delivery controls before approval.
 Oct 01, 2026Multiaxial Material Fatigue Analysis for Predicting Service Life Under Variable LoadsMultiaxial material fatigue analysis helps predict service life under variable loads, enabling safer procurement, lower lifecycle risk, and durable tourism infrastructure.
 Sep 28, 2026What Does Tourism Destination Infrastructure Cost? A Budgeting Guide for DevelopersTourism destination infrastructure price guide for developers: budget utilities, systems, installation, lifecycle costs, and contingencies for smarter investments.
 Sep 26, 2026Regulatory Compliance Procurement Support: How to Vet Suppliers Before Contract AwardRegulatory compliance procurement support helps buyers vet suppliers, verify evidence, manage risks, and secure compliant assets before contract award.
 Sep 15, 2026System Integration Testing for Device Integration: Key Interfaces and Failure RisksSystem integration testing device integration: identify critical interfaces, hidden failure risks, recovery gaps, and acceptance evidence before connected devices go live.
 Sep 01, 2026How to Use a Tourism Standards Database to Verify Safety and Compliance RequirementsTourism standards database guide: verify safety, compliance, evidence scope, test conditions, and jurisdiction requirements with confidence.
 Aug 31, 2026Material Performance Validation: Tests and Acceptance Criteria for Critical PartsMaterial performance validation: discover essential tests and acceptance criteria that help critical parts withstand loads, corrosion, fatigue, and real-world service conditions.
 Aug 26, 2026What Is a CMS and How Do You Choose One for a Growing Business Website?CMS explained for growing business websites: learn how to choose a CMS that supports SEO, workflows, integrations, and long-term scalability without costly rebuilds.
 Aug 24, 2026How to Build a Technical Procurement Content Workflow for Faster Vendor EvaluationTechnical procurement content workflow strategies for faster vendor evaluation: standardize intake, compare evidence clearly, surface risks early, and cut costly procurement delays.
 Aug 20, 2026How to Evaluate Sustainable Concrete Alternatives for Low-Carbon Building ProjectsSustainable concrete alternatives: learn how to compare carbon data, structural performance, code compliance, and supply risk to choose low-carbon concrete solutions with confidence.
 Aug 17, 2026What Does Product Category Insights Reveal About Buyer Demand and Market Positioning?Product category insights reveal buyer demand, key product attributes, and market positioning. Learn how to spot reliable signals, compare segments, and make smarter decisions.
 Aug 13, 2026How to Use Industry Benchmarking to Improve Specification Planning DecisionsIndustry benchmarking for specification planning helps technical evaluators make smarter procurement decisions, reduce risk, and improve long-term performance with evidence-based standards.
 Aug 12, 2026Technical Certification Pricing Model: What Drives Cost and How to Compare QuotesTechnical certification pricing model explained: learn what drives cost, spot hidden risks in low quotes, and compare certification proposals with confidence before you approve budget.
 Aug 09, 2026How to Evaluate Tourism Equipment for Eco Resorts Without Compromising Guest ExperienceTourism equipment evaluation for eco resorts made practical: learn how to balance sustainability, durability, and guest comfort to avoid costly mistakes and choose smarter.
 Aug 07, 2026How to Evaluate LEED Standards for Environmental Sustainability in Building ProjectsEnvironmental sustainability assessment LEED standards explained: learn how to evaluate prerequisites, credits, costs, and project risks to achieve smarter, more reliable green building outcomes.
 Aug 05, 2026Why Eco Structures in the Middle East Are Shifting Toward Modular, Off-Grid DesignsEco structures in Middle East markets are moving to modular, off-grid designs for faster delivery, lower operating risk, and stronger climate resilience. Discover what is driving the shift.
 Jul 30, 2026Industry Insights for Market Expansion: How to Identify High-Potential Regions?Industry insights for market expansion: learn how to identify high-potential regions by assessing demand, infrastructure, compliance, and supply chain readiness for smarter growth.
 Jul 14, 2026How to Apply a Tourism Innovation Validation Framework to Assess New Visitor ProjectsTourism innovation validation framework explained: learn how to assess new visitor projects, reduce delivery risk, verify compliance, and make smarter investment decisions.
 Jul 13, 2026Import Market Research Checklist: How to Assess Demand, Tariffs, and Supplier RiskImport market research made practical: learn how to assess real demand, model tariffs, and reduce supplier risk with a clear checklist for smarter sourcing decisions.
 Jul 11, 2026Fade Resistant Durability: Which Test Methods Matter for Long-Term Outdoor Use?Fade resistant durability starts with the right test data. Discover which methods best predict long-term outdoor performance, color stability, and lower lifecycle risk.
 Jul 09, 2026Electronic Gadgets for Travel and Daily Use: How to Pick Features That MatterElectronic gadgets for travel and daily use should deliver real value. Learn how to compare battery life, portability, durability, and connectivity before you buy.
 Jul 08, 2026Regulatory Compliance Framework Explained: Core Elements, Gaps, and Audit ReadinessRegulatory compliance framework explained for modern organizations: learn core elements, common gaps, and audit readiness strategies to reduce risk, improve control, and strengthen decisions.
![]() Jul 07, 2026Faucets and Mixers Buying Guide: Types, Valve Options, and Finish SelectionFaucets and mixers buying guide covering fixture types, valve options, and finish selection. Compare durability, comfort, maintenance, and performance before you buy.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.