Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- How to Plan Outdoor Kinetic Art Installations for Parks, Resorts, and Public SpacesOutdoor kinetic art planning guide for parks, resorts, and public spaces—explore safety, engineering, materials, lifecycle costs, and maintenance for lasting visitor impact.
- Amusement Equipment Testing for Family Entertainment Centers: Key Safety ChecksAmusement equipment testing for family entertainment centers: discover essential safety checks for restraints, brakes, interlocks, structural wear, and daily operations.
- What Engineering Performance Testing Should Cover During a Specification ReviewEngineering performance testing for specification review: learn how to verify structural strength, durability, safety, sustainability, and system reliability before costly project decisions.
Popular Tags
TerraVista Metrics (TVM)Industry NewsWhy Eco Structures in the Middle East Are Shifting Toward Modular, Off-Grid Designs
auth.Time
Sep 05, 2026Click Count
Why Eco Structures in the Middle East Are Shifting Toward Modular, Off-Grid Designs
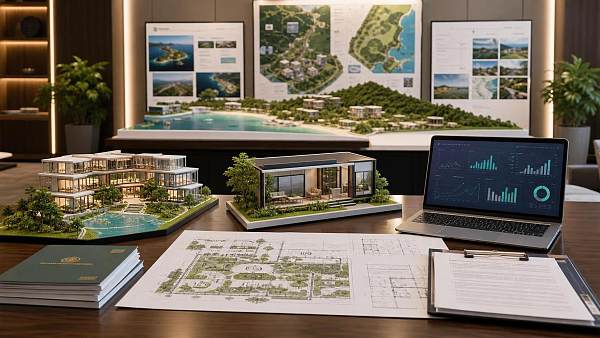
Why are eco structures in Middle East markets increasingly moving toward modular, off-grid designs? For developers, operators, and procurement leaders, the answer lies in a mix of climate resilience, faster deployment, lower lifecycle costs, and rising sustainability demands. This shift is not just an architectural trend; it reflects a practical response to regional tourism growth, infrastructure constraints, and the need for high-performance assets that can deliver durable, scalable guest experiences.
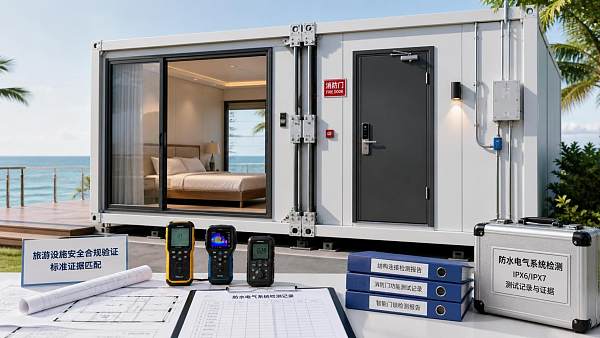
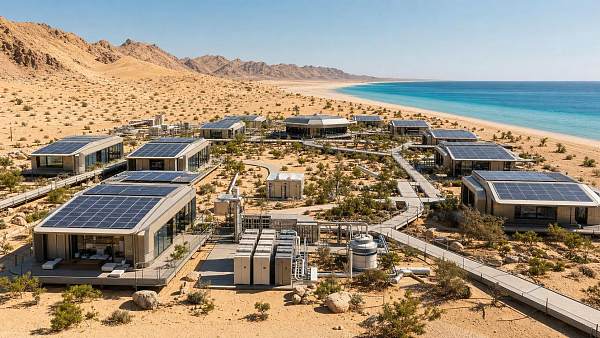
What has changed over the past few years is not simply design taste. The commercial logic behind remote hospitality projects has hardened. In Saudi Arabia, the UAE, Oman, and parts of North Africa, tourism investment is moving beyond conventional city hotels into desert retreats, coastal eco-resorts, heritage landscapes, and low-density experiential lodging. Many of these sites sit far from stable utilities, heavy logistics corridors, or mature contractor networks. That reality is forcing a different build model. Permanent-looking assets still matter, but the route to getting them operational is shifting toward prefabricated units, hybrid energy systems, dry construction methods, and structures that can function with limited dependence on local grids.
The key point is that off-grid no longer signals compromise. In earlier cycles, it often implied temporary infrastructure or a niche sustainability story. Now it is increasingly evaluated as an operating strategy. For owners trying to open remote sites on schedule, control capex volatility, and limit exposure to utility delays, modular off-grid design offers something conventional construction often struggles to provide in these environments: predictability.
Climate Pressure Is Reshaping the Asset Specification
Heat, dust, salinity, and water scarcity are not new in the Middle East. What is changing is how directly they now affect procurement decisions. Developers are becoming less willing to treat environmental performance as a branding layer added after concept design. In remote hospitality, a structure’s thermal envelope, ventilation strategy, corrosion resistance, and water system efficiency have immediate cost consequences. If a unit cannot maintain livable internal conditions without excessive cooling loads, the problem appears quickly in diesel consumption, battery sizing, maintenance frequency, and guest complaints.
This is one reason modular eco structures are gaining traction. Factory-built systems allow tighter control over insulation assemblies, glazing specifications, structural tolerances, and service integration before units ever reach site. In harsh climates, that matters. Field-built projects often lose performance in the gap between drawings and execution, especially where labor conditions are variable and skilled installation teams are stretched across multiple developments.
For operators, the conversation has moved from “Is the unit sustainable?” to “How much energy does it need in August, how often does the envelope degrade in windblown sand, and what happens to uptime if water delivery is interrupted?” That is a more serious conversation, and it favors measurable building performance over visual eco-language.
Remote Tourism Growth Has Exposed Infrastructure Limits
The Middle East’s tourism pipeline increasingly includes destinations where the site itself is the product: desert astronomy camps, wellness retreats, protected coastal areas, mountain lodges, and conservation-linked stays. These projects are commercially attractive because they differentiate from urban inventory and align with demand for experience-led travel. But they also expose an old constraint. Infrastructure expansion rarely moves at the same speed as hospitality ambition.
Grid connection lead times, water access, wastewater handling, and road logistics can delay openings or force redesign. For a developer, every month of delay hits financing costs and revenue forecasts. Modular construction reduces part of that risk by shifting more work into manufacturing environments while civil works progress on site. Off-grid systems reduce another part by lowering dependence on external utility completion. Even when full autonomy is not the target, partial independence can protect a project from weak infrastructure sequencing.
This matters especially in phased developments. Operators can open a first cluster of keys, test guest demand, refine staffing, and add capacity later without rebuilding the entire service backbone. That flexibility fits the current market better than oversizing fixed infrastructure from day one.
Speed Is Not the Only Modular Advantage
It is easy to reduce the modular argument to faster construction, but that misses the deeper financial appeal. In this market, speed matters because it shortens time to revenue. Yet the more durable reason for adoption is control. Modular systems can reduce site labor intensity, narrow quality variation, and simplify repeat deployment across multiple locations. For groups building branded eco-lodging portfolios rather than one-off flagships, that repeatability is valuable.
There is also a supply-chain angle. Global prefabrication networks have matured, and buyers now have broader access to specialist manufacturers producing high-performance cabins, lightweight steel systems, advanced composites, integrated MEP pods, and smart energy packages. That does not eliminate procurement risk; it changes its shape. Buyers must now evaluate shipping dimensions, local code alignment, after-sales service, spare part availability, and climate suitability with more discipline. But for many projects, those are manageable risks compared with the uncertainty of remote conventional builds.
At TerraVista Metrics, this is where technical benchmarking becomes more important than brochure language. Units that appear similar at concept stage can diverge sharply in insulation continuity, material durability, HVAC integration, and monitoring capability. In the Middle East, those differences show up fast once occupancy begins.
Why Off-Grid Design Is Becoming Commercially Rational
Off-grid design in this region is usually less about complete disconnection than about controlled dependence. Solar generation, battery storage, greywater reuse, high-efficiency cooling, low-flow fixtures, composting or packaged wastewater treatment, and digital energy management are being combined to reduce utility loads and increase operating resilience. The commercial case strengthens in sites where diesel transport is expensive, water trucking is unstable, or future utility tariffs are uncertain.
There is also a brand dimension, but it is no longer enough on its own. Guests may respond well to sustainability narratives, particularly in premium eco-tourism, but owners are now asking whether the engineering can support that story over ten years of operation. If an “eco” resort requires excessive generator backup, frequent component replacement, or high water losses, the narrative erodes quickly. The better projects are treating off-grid systems as operational infrastructure first and guest-facing sustainability second.
That shift aligns with broader disclosure pressure. Across global hospitality and real estate, investors, operators, and public-sector stakeholders are paying closer attention to energy use, carbon exposure, and resource efficiency. Middle East projects serving international tourism demand are not insulated from that scrutiny, even when local enforcement pathways differ by country. Assets that can document actual performance are likely to be favored over assets that only claim green intent.
What Buyers Are Starting to Screen More Closely
A visible market shift is happening in procurement language. Buyers are asking fewer generic questions about sustainability credentials and more detailed questions about performance under site-specific conditions. In practice, that means more attention to:
That screening behavior is a useful signal. It suggests the market is moving beyond concept-stage enthusiasm and into operational discipline. Suppliers that cannot provide credible technical documentation are likely to struggle, especially in larger developments backed by institutional capital or public-private partnerships.
The Aesthetic Is Becoming Secondary to the Operating Model
One subtle but important shift is that the visual language of eco structures is becoming less decisive. Earlier projects often leaned heavily on distinctive forms, natural finishes, or “immersive” storytelling. Those features still sell rooms, but they no longer carry the deal on their own. The harder question is whether the asset can maintain guest comfort and service reliability in isolated terrain without turning operations into a permanent troubleshooting exercise.
That is why some of the strongest modular concepts now look more engineered than romantic. Better sealing details, service access, equipment redundancy, replaceable components, and remote system monitoring may not photograph as well as dramatic design gestures, but they matter more after launch. Procurement teams are paying attention.
What Could Slow the Shift
The direction is clear, but it is not frictionless. Country-level permitting frameworks still vary, and imported modular systems do not always align cleanly with local approvals, fire expectations, utility interfaces, or transport constraints. Some developers also underestimate the commissioning complexity of hybrid off-grid systems. A modular unit can arrive quickly and still perform poorly if controls, shading, drainage, or operator training are weak.
There is also a financing question. Lenders and investors often understand conventional real estate assumptions better than modular asset models, especially where resale value, depreciation treatment, or warranty enforcement are unclear. That will likely improve as more projects build operating histories, but for now, documentation quality and performance transparency remain decisive.
Another point worth watching is standardization risk. Repeatable systems are commercially attractive, yet over-standardized designs can fail when copied across desert, coastal, mountain, and heritage locations without climate-specific adaptation. The next phase of the market will reward platforms that are modular in manufacturing logic but responsive to local environmental demands.
What to Watch Next
The strongest indicator over the next two to three years will not be the number of projects branding themselves as eco-resorts. It will be whether developers start specifying verified thermal performance, monitored energy intensity, water reuse capability, and maintenance thresholds earlier in the buying cycle. Once those requirements become standard in tenders, the shift to modular, off-grid designs will be less a niche movement and more a baseline expectation for remote hospitality assets.
For anyone tracking eco structures in Middle East markets, that is the real inflection point. The winners are unlikely to be the suppliers with the most polished sustainability language. They will be the ones that can prove resilience, deployment reliability, and operational efficiency under regional conditions that leave very little room for vague claims.
Recommended News
 Sep 01, 2026How to Use a Tourism Standards Database to Verify Safety and Compliance RequirementsTourism standards database guide: verify safety, compliance, evidence scope, test conditions, and jurisdiction requirements with confidence.
 Aug 31, 2026Material Performance Validation: Tests and Acceptance Criteria for Critical PartsMaterial performance validation: discover essential tests and acceptance criteria that help critical parts withstand loads, corrosion, fatigue, and real-world service conditions.
 Aug 26, 2026What Is a CMS and How Do You Choose One for a Growing Business Website?CMS explained for growing business websites: learn how to choose a CMS that supports SEO, workflows, integrations, and long-term scalability without costly rebuilds.
 Aug 24, 2026How to Build a Technical Procurement Content Workflow for Faster Vendor EvaluationTechnical procurement content workflow strategies for faster vendor evaluation: standardize intake, compare evidence clearly, surface risks early, and cut costly procurement delays.
 Aug 20, 2026How to Evaluate Sustainable Concrete Alternatives for Low-Carbon Building ProjectsSustainable concrete alternatives: learn how to compare carbon data, structural performance, code compliance, and supply risk to choose low-carbon concrete solutions with confidence.
 Aug 17, 2026What Does Product Category Insights Reveal About Buyer Demand and Market Positioning?Product category insights reveal buyer demand, key product attributes, and market positioning. Learn how to spot reliable signals, compare segments, and make smarter decisions.
 Aug 13, 2026How to Use Industry Benchmarking to Improve Specification Planning DecisionsIndustry benchmarking for specification planning helps technical evaluators make smarter procurement decisions, reduce risk, and improve long-term performance with evidence-based standards.
 Aug 12, 2026Technical Certification Pricing Model: What Drives Cost and How to Compare QuotesTechnical certification pricing model explained: learn what drives cost, spot hidden risks in low quotes, and compare certification proposals with confidence before you approve budget.
 Aug 09, 2026How to Evaluate Tourism Equipment for Eco Resorts Without Compromising Guest ExperienceTourism equipment evaluation for eco resorts made practical: learn how to balance sustainability, durability, and guest comfort to avoid costly mistakes and choose smarter.
 Aug 07, 2026How to Evaluate LEED Standards for Environmental Sustainability in Building ProjectsEnvironmental sustainability assessment LEED standards explained: learn how to evaluate prerequisites, credits, costs, and project risks to achieve smarter, more reliable green building outcomes.
 Aug 05, 2026Why Eco Structures in the Middle East Are Shifting Toward Modular, Off-Grid DesignsEco structures in Middle East markets are moving to modular, off-grid designs for faster delivery, lower operating risk, and stronger climate resilience. Discover what is driving the shift.
 Jul 30, 2026Industry Insights for Market Expansion: How to Identify High-Potential Regions?Industry insights for market expansion: learn how to identify high-potential regions by assessing demand, infrastructure, compliance, and supply chain readiness for smarter growth.
 Jul 14, 2026How to Apply a Tourism Innovation Validation Framework to Assess New Visitor ProjectsTourism innovation validation framework explained: learn how to assess new visitor projects, reduce delivery risk, verify compliance, and make smarter investment decisions.
 Jul 13, 2026Import Market Research Checklist: How to Assess Demand, Tariffs, and Supplier RiskImport market research made practical: learn how to assess real demand, model tariffs, and reduce supplier risk with a clear checklist for smarter sourcing decisions.
 Jul 11, 2026Fade Resistant Durability: Which Test Methods Matter for Long-Term Outdoor Use?Fade resistant durability starts with the right test data. Discover which methods best predict long-term outdoor performance, color stability, and lower lifecycle risk.
 Jul 09, 2026Electronic Gadgets for Travel and Daily Use: How to Pick Features That MatterElectronic gadgets for travel and daily use should deliver real value. Learn how to compare battery life, portability, durability, and connectivity before you buy.
 Jul 08, 2026Regulatory Compliance Framework Explained: Core Elements, Gaps, and Audit ReadinessRegulatory compliance framework explained for modern organizations: learn core elements, common gaps, and audit readiness strategies to reduce risk, improve control, and strengthen decisions.
![]() Jul 07, 2026Faucets and Mixers Buying Guide: Types, Valve Options, and Finish SelectionFaucets and mixers buying guide covering fixture types, valve options, and finish selection. Compare durability, comfort, maintenance, and performance before you buy.
 Jul 06, 2026Tourism Equipment Specification Review: Which Ratings Matter Before You Buy?Tourism equipment specification review made practical: learn which ratings truly affect safety, lifecycle cost, compliance, and uptime before you choose a supplier.
 Jul 05, 2026What Is Material Fatigue in Composites? Failure Mechanisms and Service Life BasicsMaterial fatigue composites explained: learn key failure mechanisms, service life factors, and how to assess durability risks before specifying composite products.
 Jul 03, 2026Tourism Destination Infrastructure in North America: What Investors and Developers Evaluate FirstTourism destination infrastructure in North America shapes returns from day one. Discover what investors and developers assess first to reduce risk, improve resilience, and protect long-term value.
 Jul 02, 2026Tourism Development Validation Methodology Explained: Metrics, Data Sources, and Use CasesTourism development validation methodology explained with key metrics, trusted data sources, and real use cases to reduce risk, improve compliance, and guide smarter tourism investment decisions.
 Jun 30, 2026Regulatory Compliance Criteria Explained: How to Evaluate Requirements by Product and MarketRegulatory compliance criteria explained clearly: learn how to assess product and market requirements, reduce approval risk, and make smarter sourcing and market-entry decisions.
 Jun 29, 2026Efficient Procurement Planning: How to Reduce Delays and Control Budget RiskEfficient procurement planning helps reduce delays, control budget risk, and improve supplier decisions with data-driven strategies for stronger project delivery.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.