Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- How to Build Stable Interoperability Across Hotel Guestroom SystemsHospitality system interoperability stable: learn how hotels can align room states, command priorities, local fallback, and testing for reliable guestroom operations.
- How to Plan Outdoor Kinetic Art Installations for Parks, Resorts, and Public SpacesOutdoor kinetic art planning guide for parks, resorts, and public spaces—explore safety, engineering, materials, lifecycle costs, and maintenance for lasting visitor impact.
- Amusement Equipment Testing for Family Entertainment Centers: Key Safety ChecksAmusement equipment testing for family entertainment centers: discover essential safety checks for restraints, brakes, interlocks, structural wear, and daily operations.
Popular Tags
TerraVista Metrics (TVM)Industry NewsRecreational Cable Transport Global Market: Key Growth Drivers and Regional Outlook
auth.Time
Sep 07, 2026Click Count
Recreational Cable Transport Global Market: Key Growth Drivers and Regional Outlook
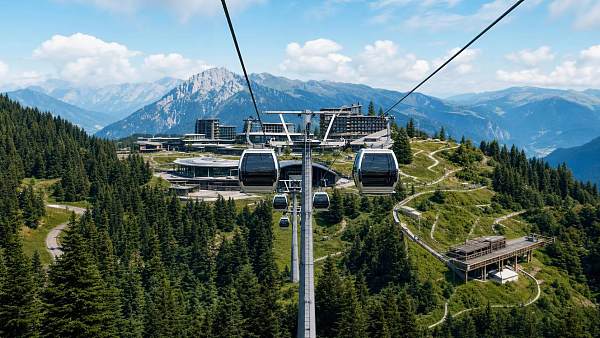
The recreational cable transport global market is moving beyond the old investment logic of “build a lift, capture peak-season traffic.” What now matters is whether a cable transport system can support year-round destination economics, meet tighter safety and environmental expectations, and stay serviceable in a supply chain that has become less forgiving. That shift is visible across mountain tourism, mixed-use leisure projects, and resort redevelopment programs, where cable mobility is increasingly assessed as part of a broader infrastructure stack rather than as a standalone attraction.
For evaluators, the most useful starting point is demand quality rather than headline volume. The strongest projects are no longer only in mature ski markets. They are in destinations where cable systems solve multiple operating problems at once: moving guests between fragmented terrain, reducing road congestion, opening difficult topography to non-winter use, and giving site operators a transport asset that can carry both visitors and service logistics. In practical terms, this favors developments that connect hospitality, retail, scenic access, and outdoor recreation into one operating model.
This is one reason the market conversation has become more technical. Procurement teams are asking harder questions about lifecycle cost, evacuation procedures, wind performance, maintenance intervals, spare-parts exposure, and interoperability with digital control systems. The commercial case is still driven by visitor demand, but approval and financing increasingly depend on engineering credibility. The distance between concept-stage renderings and buildable, certifiable infrastructure has become more visible, especially in projects where cable transport is expected to anchor a premium tourism proposition.
Why growth is broadening beyond traditional ski corridors
Several long-running trends are converging. Mountain destinations are trying to smooth revenue outside peak snow periods. Urban-edge leisure zones are under pressure to improve visitor flow without expanding roads or parking. Governments and local planners, particularly in environmentally sensitive areas, are more willing to consider low-footprint mobility systems when compared with conventional hillside access works. None of this guarantees project viability, but it does widen the strategic use cases for gondolas, aerial tramways, detachable chairlifts, and hybrid systems.
Climate variability also changes the investment lens. In snow-reliant resorts, capital expenditure is being judged against all-season resilience, not just winter throughput. A lift line that supports sightseeing, mountain biking, hiking access, hospitality-linked circulation, and event programming has a different risk profile from one tied almost entirely to ski-pass volume. That distinction matters in financing discussions, because lenders and owners are increasingly alert to weather concentration risk even when they do not say so directly.
There is also a quieter but important demand shift: visitors are more accepting of cable systems as part of the leisure experience itself. Scenic transport, once treated as secondary infrastructure, is now part of destination positioning. That does not mean every installation becomes an attraction, but it does raise expectations around ride quality, station design, accessibility, digital ticketing, and integration with hospitality services. Operators that ignore this often underestimate the commercial downside of poor queue management or unreliable uptime.
The market is being shaped as much by standards and serviceability as by demand
The sector has always been regulation-heavy, but current decision-making is more sensitive to compliance pathways and operating responsibility. Recreational cable transport sits at the intersection of transport engineering, public safety, environmental permitting, and destination operations. In Europe, the regulatory environment remains relatively mature, and that tends to favor projects with clearer technical documentation and established supplier support. In other regions, the variation is wider. Some markets have clear frameworks for ropeway approval and inspection; others require developers to navigate a patchwork of local construction, tourism, and safety rules.
That complexity makes independent technical review more valuable. TerraVista Metrics’ work across tourism infrastructure categories points to a pattern seen well beyond cable systems: buyers are more cautious about accepting performance claims at face value. They want validated information on mechanical endurance, system integration, materials behavior, and maintenance realism under actual site conditions. In cable transport, that often translates into closer scrutiny of component origin, corrosion exposure, emergency systems, software architecture, and the practical availability of trained service personnel after commissioning.
The implication is straightforward. Market growth will not be captured only by manufacturers with the largest installed base, but by those that can demonstrate dependable after-sales support, spare-parts continuity, and regulatory fluency across jurisdictions. In a more volatile project environment, serviceability becomes part of market access.
Regional outlook is diverging, not converging
Europe remains the reference point for engineering maturity, refurbishment activity, and operator experience. A large installed base creates recurring demand for modernization, automation upgrades, energy-efficiency improvements, and replacement of aging lift infrastructure. Growth here may look less dramatic than in emerging leisure markets, but it is often more bankable because the operational and regulatory context is better understood. Refurbishment can also be strategically attractive where terrain and permitting constraints make new alignments difficult.
North America is likely to remain a mixed picture. Established mountain resorts continue to invest, yet the rationale has broadened from skier uplift alone to broader destination mobility and guest experience management. At the same time, project economics can be pressured by labor scarcity, construction cost inflation, and long lead times for specialized equipment. Buyers in this region often place high value on reliability and long-term maintainability because unplanned downtime carries heavy reputational and revenue costs in premium resort settings.
Asia-Pacific offers some of the most interesting upside, but also the widest execution gap between ambition and delivery. Demand drivers include domestic tourism growth, mountain resort development, and integrated leisure destinations seeking transport solutions that also function as signature experiences. Yet regional variation is substantial. Some projects benefit from strong public backing and large-scale destination planning; others move faster on concept than on engineering readiness. The better opportunities are usually where transport planning, hospitality development, and environmental review are sequenced together rather than treated as separate workstreams.
Latin America, the Middle East, and selected parts of Africa are best viewed as opportunity clusters rather than uniform growth regions. Scenic tourism, upland resort development, and landmark destination projects can support cable transport investment, but procurement risk tends to hinge on import exposure, maintenance capability, currency instability, and the maturity of local inspection regimes. In these markets, a technically sound project can still struggle if the operating ecosystem is thin.
Technology adoption is getting more operational
One of the clearer changes in the recreational cable transport global market is that technology conversations are becoming less promotional and more operational. Digital monitoring, predictive maintenance tools, automated control systems, and integrated ticketing have all been discussed for years. What has changed is the buyer’s threshold for usefulness. Operators want systems that reduce avoidable stoppages, simplify maintenance planning, support compliance documentation, and fit into wider smart-destination infrastructure.
This creates a sharper distinction between genuine technical integration and surface-level digitalization. A modern ropeway linked to access control, visitor analytics, hotel systems, and maintenance software can improve planning and throughput. But integration also introduces cyber, interoperability, and vendor-dependence questions that many tourism developers are only beginning to price properly. For that reason, technology adoption is likely to keep advancing, though not evenly. Buyers with complex, high-volume destinations will move faster than single-asset operators with limited technical staff.
Energy performance is another area to watch, even if the market narrative can become overstated. Rising electricity costs and decarbonization goals push operators toward more efficient drive systems, improved load management, and, where practical, tighter alignment between transport operations and site-wide energy strategies. The business case varies by region and tariff structure, so blanket claims are unhelpful. Still, equipment efficiency and operational energy demand are no longer side issues in capex reviews.
What could slow the market
Not every positive demand signal converts into orders. The market remains vulnerable to long development cycles, financing sensitivity, and local opposition where landscape impact is contested. Specialized component lead times and concentrated supplier ecosystems can complicate schedules. On the operator side, technical workforce depth is a practical constraint, especially in newer markets where rescue readiness, maintenance discipline, and inspection routines depend heavily on external support.
There is also the risk of strategic overreach. Some destinations still treat cable transport as a symbolic marker of premium tourism rather than as a system that must fit terrain realities, visitor mix, weather conditions, and long-term operating budgets. Those projects tend to look persuasive in early-stage commercial decks and weaker under engineering review. In the next few years, the market is likely to reward disciplined schemes more than ambitious but thinly specified ones.
The most useful signals to track are not generic growth claims but practical indicators: modernization activity in mature regions, tender quality in emerging markets, supplier backlog visibility, service-network expansion, and the extent to which destination projects are budgeting for lifecycle support rather than just installation. Those signals usually tell more about market health than broad tourism optimism.
For business evaluators, that is the central takeaway. The market still has room to expand, particularly where leisure mobility, destination design, and technical governance are being planned together. But the investable edge is shifting toward projects and suppliers that can prove durability, compliance readiness, and operational continuity. In recreational cable transport, demand is real. The harder question is which assets can keep performing once the launch period is over. That is where the next phase of market separation is likely to happen.
Recommended News
 Aug 28, 2026What Do Standardized Performance Benchmarks Cost, and What Do Buyers Get?Standardized performance benchmarks price explained: compare costs, scope, and buyer deliverables to reduce procurement risk and make confident investment decisions.
 Aug 03, 2026How to Read a Compliance Analysis Report Before Supplier ApprovalCompliance analysis report guide: learn how to verify scope, evidence, exclusions, and risk before supplier approval, helping you avoid costly compliance gaps and make smarter sourcing decisions.
 Aug 02, 2026What Should Executives Look for in a Market Intelligence Report Dashboard?Market intelligence report dashboard essentials for executives: learn how to spot decision-ready insights, benchmark risk, source confidence, and business impact before making high-stakes moves.
 Jul 29, 2026Recreational Cable Transport Global Market: Key Growth Drivers and Regional OutlookRecreational cable transport global market analysis explores key growth drivers, regional outlook, technology shifts, and investment risks shaping future leisure mobility opportunities.
 Jul 26, 2026Tourism Development Report: Key Market Signals, Investment Priorities, and Growth RisksTourism development report on market signals, investment priorities, and growth risks—discover where tourism assets can deliver resilient returns, sustainability value, and smarter expansion.
 Jul 25, 2026How to Evaluate a Standardized Performance Benchmarks Research Firm?Standardized performance benchmarks research firm selection starts with method, independence, and industry fit. Learn how to compare firms and choose evidence that supports smarter procurement decisions.
 Jul 18, 2026How to Read a Prefab Durability Testing Report Before Specifying Modular UnitsPrefab durability testing report essentials: learn how to assess test scope, standards, margins, and hidden risks before specifying modular units with confidence.
 Jul 15, 2026How a Market Intelligence Agency Supports Supplier Screening and Market Entry DecisionsA market intelligence agency helps businesses screen suppliers, reduce entry risk, and make smarter market decisions with verified data, compliance insight, and actionable analysis.
 Jul 14, 2026Project Planning Intelligence Tools: Which Features Matter for Cross-Functional Teams?Project planning intelligence tools for cross-functional teams: discover the must-have features for risk, compliance, forecasting, and smarter project decisions.
 Jul 13, 2026Tourism Equipment Market Evaluation: Which Demand, Price, and Channel Metrics Matter?Tourism equipment market evaluation reveals which demand, price, and channel metrics truly drive margins, reduce risk, and improve procurement decisions across modern tourism projects.
 Jul 11, 2026Compliance Analysis USA: How to Review Testing and Documentation Before BuyingCompliance analysis USA made practical: learn how to verify test reports, certification scope, and documentation before buying to reduce sourcing risk, control costs, and choose suppliers with confidence.
 Jul 10, 2026How to Compare Product Category Market Price Across Suppliers Without Missing Hidden CostProduct category market price comparison goes beyond the lowest quote. Learn how to uncover hidden costs across suppliers and make smarter, lower-risk buying decisions.
 Jul 08, 2026Presentation Tools Compared: Which Features Matter for Team Training and Demos?Presentation tools compared for team training and demos: discover which features improve collaboration, technical clarity, and reliable delivery across real operational workflows.
![]() Jul 07, 2026Tourism Supply Chain Analysis in North America: Key Cost Drivers and BottlenecksTourism supply chain analysis North America reveals key cost drivers, freight risks, compliance pressure, and integration bottlenecks—helping tourism projects cut risk and make smarter investment decisions.
 Jul 03, 2026On Site Thermal Efficiency Testing: When It’s Required and Which Metrics Matter MostOn site thermal efficiency testing reveals how buildings perform in real conditions. Learn when it’s required, which metrics matter most, and how to reduce energy risk.
 Jul 02, 2026What Drives Industry Reports Cost Factors: Data Scope, Method, and Update FrequencyIndustry reports cost factors explained: see how data scope, research method, and update frequency shape report value, pricing, and smarter investment decisions.
 Jun 30, 2026Fashion Trends 2026: Which Materials, Silhouettes, and Colors Are Shaping New Collections?Fashion trends 2026 reveal the materials, silhouettes, and colors shaping scalable new collections. Discover buyer-ready insights on comfort, utility, and strategic color direction.
 Jun 27, 2026Tourism Asset Evaluation Cost Factors: What Drives Valuation in Resort Projects?Tourism asset evaluation cost factors shape resort valuation through site complexity, compliance, smart systems, and lifecycle risk. See what really drives cost and stronger investment decisions.
 Jun 25, 2026How to Use Material Sustainability Analysis in Product Selection and Supplier EvaluationMaterial sustainability analysis helps buyers compare real lifecycle value, durability, compliance, and supplier reliability. Learn how to make smarter product selection decisions.
 Jun 21, 2026Tourism Carbon Metrics: How Hotels and Destinations Measure Emissions in PracticeTourism carbon in practice: learn how hotels and destinations measure emissions, set clear boundaries, compare assets fairly, and turn data into credible low-carbon decisions.
 Jun 20, 2026What Affects Outdoor Furniture Price? Materials, Durability, MOQ, and Shipping CostsOutdoor furniture price depends on more than design. Explore how materials, durability, MOQ, customization, and shipping costs shape real project value and smarter buying decisions.
 Jun 19, 2026How to Read a Compliance Standards Assessment Report for Supplier ApprovalCompliance standards assessment report guide for smarter supplier approval. Learn how to verify scope, findings, risks, and evidence quality before you commit.
 Jun 14, 2026Emerging Markets Outlook: 5 Supply Chain Shifts Reshaping Global SourcingEmerging markets are reshaping global sourcing through resilience, compliance, smart manufacturing, sustainability, and category-specific insight. Discover 5 shifts buyers can’t ignore.
 Jun 13, 2026Export Import Compliance Checklist: Key Documents, HS Codes, Duties, and Common DelaysExport import compliance checklist covering key documents, HS codes, duties, and common delay risks. Learn how to reduce customs issues, control landed cost, and keep shipments moving.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.