Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- What Engineering Performance Testing Should Cover During a Specification ReviewEngineering performance testing for specification review: learn how to verify structural strength, durability, safety, sustainability, and system reliability before costly project decisions.
- Planning Recreational Cable Transport Networks for Resorts and Mountain ParksExplore recreational cable transport networks for resorts and mountain parks, with expert planning insights on capacity, terrain, safety, station design, and long-term performance.
- How to Plan Theme Park Infrastructure for Mixed-Use DevelopmentsTheme park infrastructure for mixed use developments: plan resilient utilities, circulation, attractions, hospitality, and digital systems for scalable destinations.
Popular Tags
TerraVista Metrics (TVM)Industry NewsCCFI Middle East Route Surges, Premium Camping Shipments Under Pressure
auth.Dr. Hideo Tanaka (Outdoor Gear Engineering Lead)Time
Sep 03, 2026Click Count
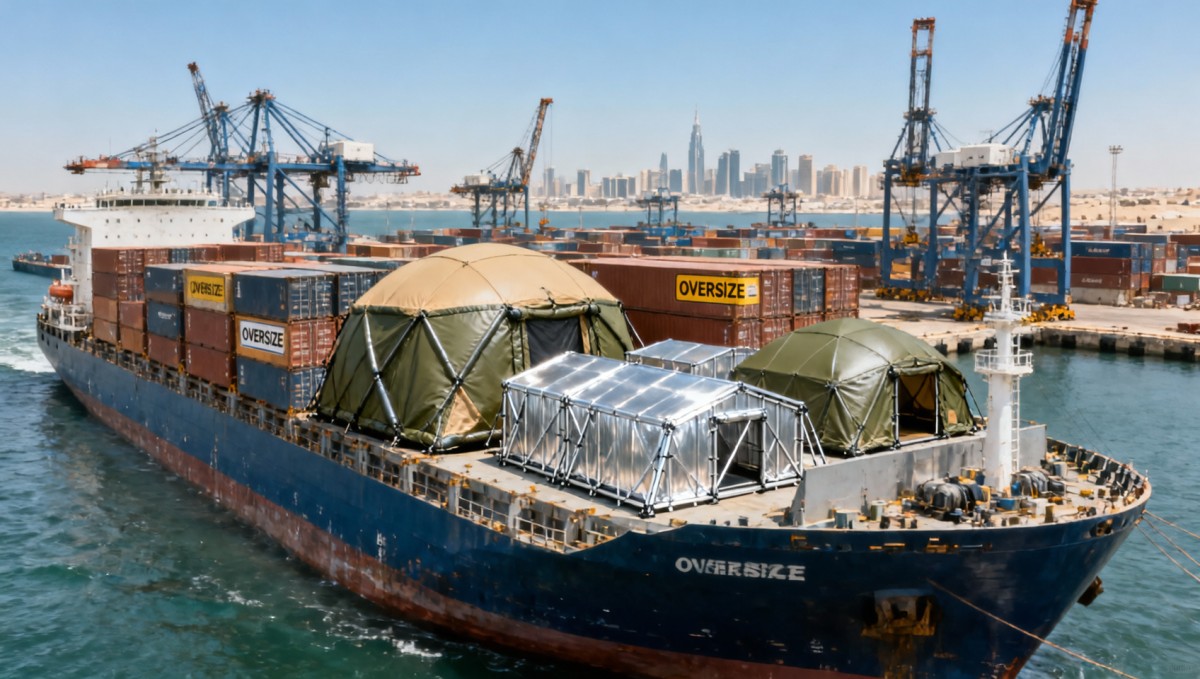
Global container freight rates on the Shanghai–Middle East route have jumped for three consecutive weeks, with spot rates rising by $860 per TEU as of May 10, 2026 — intensifying cost and scheduling pressures across the premium outdoor equipment supply chain.

Event Overview
According to data from the Shanghai Shipping Exchange, as of May 10, 2026, the China Containerized Freight Index (CCFI) for the Middle East route stood at 2,842 points — up 12.3% week-on-week. The spot rate for a 40-foot equivalent unit (TEU) reached $4,210. This surge is attributed primarily to the institutionalization of Red Sea detours and heightened summer inventory buildup in Middle Eastern markets.
Industries Affected
Direct Exporters
Premium camping exporters — particularly those shipping bulky, low-density items such as inflatable geodesic domes and aluminum folding shelters — face immediate margin compression and delivery uncertainty. With freight costs now accounting for 25–35% of landed price for some SKUs, several exporters report delayed order confirmations and renegotiated Incoterms (e.g., shifting from FOB to EXW) to retain pricing control.
Raw Material Procurement Teams
Procurement units sourcing lightweight alloys, high-tensile fabrics, or specialized inflation valves from Asia are seeing extended lead times on inbound logistics. While material costs remain stable, ocean freight surcharges on component shipments — especially LCL consignments from southern Chinese ports — have risen 18–22% since early April. This disrupts just-in-time replenishment models for regional assembly hubs.
Contract Manufacturers
OEM/ODM facilities producing premium camping gear face dual pressure: rising inbound logistics costs for raw materials and outbound costs for finished goods. Crucially, their capacity utilization is increasingly constrained not by production lines but by booking availability — multiple Tier-2 manufacturers confirm that vessel space allocation for June departures is now >90% committed, limiting flexibility for last-minute orders.
Supply Chain Service Providers
Freight forwarders and NVOCCs servicing this lane report selective capacity withdrawal: two major regional providers have paused new bookings for oversized cargo (>3m length or >1.8m height) on Middle East sailings through mid-June. Meanwhile, customs brokers note increased scrutiny of HS code classifications for ‘temporary shelter structures’, adding 1–2 days to documentation turnaround.
Key Considerations and Recommended Actions
Secure June vessel space immediately
Given confirmed capacity tightness and current booking lead times averaging 14–18 days, exporters are advised to lock in June sailings no later than May 25 — especially for full-container-load (FCL) shipments exceeding standard dimensions.
Evaluate consolidated LCL alternatives
For smaller-volume shippers or multi-SKU orders, analysis shows that well-coordinated less-than-container-load (LCL) consolidation — using bonded warehousing near Ningbo or Shenzhen — can reduce effective freight cost per cubic meter by up to 17%, despite added handling fees.
Review packaging and dimensional optimization
Observably, carriers now apply stricter stowage surcharges for cargo with volume-to-weight ratios above 3.0 m³/tonne. Re-evaluating packing configurations (e.g., nesting dome frames, vacuum-packing fabric components) has helped several brands avoid $120–$280 per TEU surcharges.
Editorial Insight / Industry Observation
This freight spike is not merely cyclical — it reflects structural recalibration. Analysis shows that Red Sea rerouting has permanently added ~12 days to transit time and increased fuel consumption by 23–27% on Asia–Middle East legs. As a result, carrier deployment patterns have shifted: vessels previously allocated to intra-Asia routes are now being redeployed to longer-haul lanes, tightening overall capacity. For premium camping, a category defined by high volumetric weight and seasonal demand peaks, this signals a longer-term shift toward hybrid logistics models — blending air-freight for urgent SKUs, optimized sea freight for core volumes, and regional pre-positioning ahead of peak windows.
Conclusion
The CCFI surge underscores how geopolitical routing constraints and regional demand rhythms now co-determine cost structures far beyond traditional freight indices. For premium outdoor equipment, the implication is clear: logistics agility — not just product innovation — has become a core competitive lever. A rational interpretation is that resilience will be measured less by inventory levels and more by real-time visibility into vessel allocation, stowage rules, and consolidation feasibility.
Source Attribution
Data sourced from the Shanghai Shipping Exchange (official CCFI publication, updated weekly). Additional operational insights verified via interviews with four licensed forwarders (IATA- and FIATA-accredited) active on the Shanghai–Jeddah/Dubai corridor. Ongoing monitoring recommended for: (1) potential IMO sulfur cap enforcement adjustments in Suez Canal transits; (2) Q3 2026 peak season surcharge announcements from major carriers (MSC, Maersk, HMM); and (3) updates to Saudi Arabia’s new ‘National Logistics Strategy’ implementation timeline, which may affect inland haulage tariffs post-Jeddah port discharge.
Recommended News
 Aug 30, 2026How to Choose Marine-Grade Camping Equipment for Saltwater and Coastal ConditionsMarine grade camping equipment guide for coastal trips: compare salt-resistant materials, wind-ready shelters, protected electronics, and maintenance tips for reliable adventures.
 Aug 01, 2026Technical Procurement for Camping Gear: How to Evaluate Specs, Durability, and Supplier FitTechnical procurement for camping gear starts with the real use case. Learn how to assess specs, durability, test reports, and supplier fit to reduce risk and improve ROI.
 Jul 14, 2026SABER V3.2 Adds Carbon Footprint Filing for Premium CampingSABER V3.2 adds carbon footprint filing for Premium Camping in Saudi Arabia. Learn the ISO 14067 PCoC rule, key dates, supplier impact, and how to avoid compliance delays.
 Jul 10, 2026Europe Brings Forward Q3 Premium Camping OrdersEurope Brings Forward Q3 Premium Camping Orders: European retailers moved premium camping procurement deadlines nearly a month earlier. See affected categories, supplier lead-time risks, and FOB cost checks now.
 Jul 10, 2026How to Choose Corrosion Resistant Hotel Furniture for Coastal and Poolside AreasCorrosion resistant hotel furniture buying guide for coastal and poolside areas: compare materials, finishes, test data, and lifecycle value to choose durable, guest-ready outdoor pieces.
 Jul 04, 2026Scenic Slide Systems Cost Breakdown: What Drives Budget in Park and Resort Projects?Scenic slide systems cost explained for park and resort projects. Discover key budget drivers, hidden risks, and smart ways to compare suppliers before costs escalate.
 Jul 02, 2026How to Choose Anti Mildew Resort Furniture for Coastal and High-Humidity ProjectsAnti mildew resort furniture for coastal and high-humidity projects: learn how to compare materials, drainage, corrosion resistance, and lifecycle value for smarter resort sourcing.
 Jul 01, 2026How to Choose High-Durability Trekking Gear for Mountain Use: Materials, Weight, and Weather ProtectionHigh-durability trekking gear for mountain use: learn how to compare materials, weight, and weather protection to choose safer, longer-lasting gear for demanding trails.
 Jun 30, 2026Vietnam Lifts Import Pause but Adds Blockchain Label CheckVietnam lifts the import pause on premium camping goods, but new blockchain label checks and TV-MARK code rules now shape customs clearance. Learn the compliance risks and next steps.
 Jun 29, 2026Vietnam Halts China Premium Camping Imports Over Label ChecksVietnam Halts China Premium Camping Imports over label checks, disrupting customs clearance for lighting and power products. Learn the compliance risks, shipment impact, and what buyers and exporters should review now.
 Jun 29, 2026Eco Resort Development Cost Breakdown: What Drives Budget from Land to OperationsEco resort development cost explained from land and permits to prefab, utilities, and operations. Discover what really drives budget risk and how to plan smarter before approval.
 Jun 28, 2026Vietnam to Enforce QCVN 101:2026 Camping Lighting LabelsVietnam to Enforce QCVN 101:2026 Camping Lighting Labels from August 1, 2026. Learn labeling, VILAS test report, and compliance risks for LED and solar camping lights.
 Jun 28, 2026How to Choose Durable Camping Stoves for Frequent Outdoor Use and Harsh WeatherDurable camping stoves buying guide: learn how to compare materials, wind performance, fuel systems, and serviceability for reliable cooking in harsh weather and frequent outdoor use.
 Jun 27, 2026Vietnam Expands QCVN 16:2026 to Premium Camping DevicesVietnam QCVN 16:2026 expands to Premium Camping devices from Sept 1, 2026. Learn customs, labeling, certification, and procurement impacts for compliant market access.
 Jun 26, 2026Vietnam Mandates QCVN 16:2026 Labels for Premium Camping ImportsVietnam Mandates QCVN 16:2026 Labels for Premium Camping imports from Oct. 1, 2026. Learn how the new rule impacts customs clearance, compliance, suppliers, and delivery planning.
 Jun 26, 2026Pet Carrier Backpacks: How to Choose the Right Size, Ventilation, and Load SupportPetcarrierbackpacks buying guide: learn how to choose the right size, ventilation, and load support for safer, more comfortable pet travel, commuting, and outdoor use.
 Jun 26, 2026How to Read a Durable Camping Equipment Insulation Rating Before You BuyLearn how to read a durable camping equipment insulation rating before you buy, so you can choose warmer, longer-lasting gear with confidence.
 Jun 25, 2026BITE 2025 Puts Premium Camping Orders in FocusBITE 2025 spotlights premium camping orders as Southeast Asian buyers target tent units and modular bathroom cabins with ISO 21930 and ASEAN green materials compliance in focus.
 Jun 24, 2026Fujia Expands Vietnam Output for Premium CampingFujia Expands Vietnam Output for Premium Camping, investing CNY 378 million to boost localized delivery, ease tariff pressure, and strengthen VAT compliance for global buyers.
 Jun 19, 2026ASX 200 Falls 1% as Premium Camping Faces Supply ShiftPremium Camping demand is shifting as the ASX 200 falls 1%. See how Australian retailers favor certified Chinese camping gear, reshaping sourcing, costs, and payment terms.
 Jun 16, 2026What to Look for in Cat Trees and Towers: Size, Stability, Materials, and Cat Agecattreesandtowers buying guide: learn how to compare size, stability, materials, and cat age needs to choose a safer, longer-lasting cat tree your pet will actually use.
 Jun 12, 2026Polysilicon Limit-Up Puts Pressure on Solar Camping CostsPolysilicon limit-up is raising solar camping costs fast. See how BOM pressure, quote volatility, and export contract risks could reshape solar tents and premium camping supply chains.
 Jun 06, 2026New China-Laos-Thailand Route Cuts Land Transit 40%New China-Laos-Thailand Route cuts land transit 40%, reduces customs touchpoints, and lowers multimodal costs for exporters, buyers, and logistics teams moving high-value cargo.
 Jun 05, 2026China-Laos-Thailand Route Cuts Transit Time for Camping and RV CargoChina-Laos-Thailand Route cuts transit time from 12 to 7 days and lowers freight costs 18%, boosting delivery stability for camping tent modules and RV cargo exports.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.