Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- How to Evaluate Spark Plug Suppliers for Consistent Quality and Lead TimesSpark plugs supplier evaluation guide: compare quality control, traceability, fitment, total cost, and reliable lead times to secure dependable engine maintenance supply.
- What Drives System Interoperability Testing Service Costs in Complex Projects?System interoperability testing service cost depends on integration scope, workflows, environments, and assurance needs. Learn how to budget smarter and reduce project risk.
- Project Planning Sourcing Guides: How to Qualify Suppliers Before Work StartsSourcing guides project planning helps teams qualify suppliers before work begins—verify compliance, delivery capacity, financial strength, and sustainability to reduce risk and protect project outcomes.
Popular Tags
TerraVista Metrics (TVM)Industry NewsWTO Outlook: Premium Camping Equipment Sea Freight Up 22% YoY
auth.Dr. Hideo Tanaka (Outdoor Gear Engineering Lead)Time
Oct 07, 2026Click Count
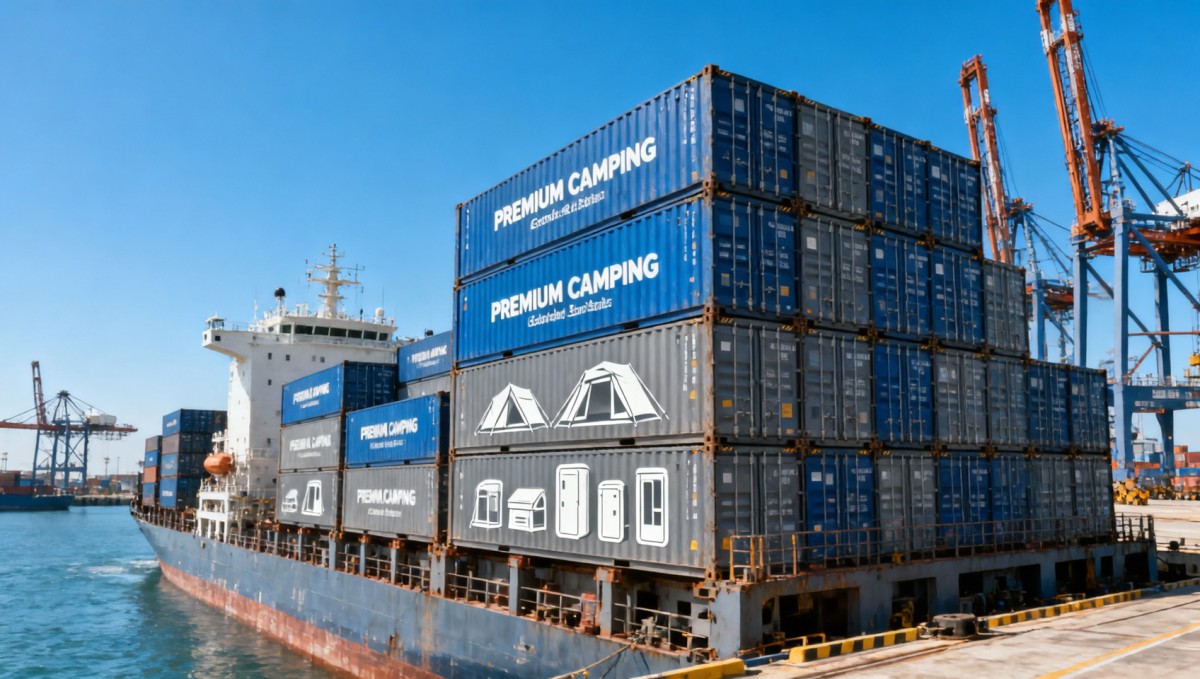
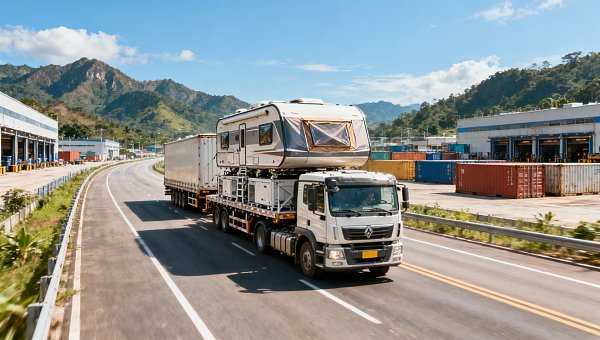
On May 18, 2026, the World Trade Organization (WTO) released its 2026 Second Quarter Global Trade Outlook, reporting a 22% year-on-year increase in sea freight rates for Premium Camping equipment—including high-end tents, mobile cabins, and eco-friendly sanitation units. This surge significantly exceeds the overall cargo average (+8.3%) and signals material cost pressures for outdoor distributors in North America and Europe. Stakeholders across global outdoor gear supply chains—particularly exporters, logistics coordinators, and wholesale channel managers—should monitor implications for pricing, inventory planning, and port-specific capacity allocation.
Event Overview
The WTO’s 2026 Second Quarter Global Trade Outlook, published on May 18, 2026, states that sea freight costs for Premium Camping equipment rose 22% year-on-year. The report attributes this to Red Sea route diversions and port congestion in the Mediterranean. The increase is notably higher than the global average freight growth of +8.3%. Chinese major export ports have introduced dedicated ‘Premium Camping Fast Lane’ container slot allocations.
Impact on Specific Industry Segments
Direct Exporters & Trading Companies: These firms face immediate margin compression due to non-negotiable carrier surcharges applied at origin. Impact manifests in delayed shipment confirmations, tighter booking windows, and reduced flexibility in multimodal routing—especially for time-sensitive seasonal orders.
Manufacturers & OEM/ODM Producers: Rising outbound logistics costs directly affect landed cost calculations and FOB-to-CIF margin assumptions. For producers shipping assembled units (e.g., pre-fitted mobile cabins), dimensional weight penalties and container availability constraints compound cost pressure beyond raw material or labor inputs.
Wholesale Distributors & Outdoor Retail Channel Operators: With freight now contributing a larger share of total landed cost, terminal pricing models require recalibration—particularly for mid-to-high-tier SKUs where premium positioning limits downward price elasticity. Inventory turnover targets may need adjustment to accommodate longer lead times and higher carrying costs.
Freight Forwarders & Port Logistics Providers: Demand for specialized handling—such as temperature-controlled stowage for eco-sanitation units or oversized cargo coordination—has intensified. However, the ‘Premium Camping Fast Lane’ initiative remains port-specific and capacity-constrained, limiting scalability without advance slot reservations.
Key Considerations and Recommended Actions
Monitor official updates on Red Sea corridor developments and EU/Mediterranean port operational advisories
While the WTO report identifies route diversion and congestion as root causes, ongoing diplomatic and security developments—such as Suez Canal Authority statements or EU port authority notices—will determine whether current conditions persist or ease in Q3 2026.
Track SKU-level freight exposure, not just category averages
Premium Camping includes structurally diverse products: compact high-end tents (lightweight, stackable) versus modular mobile cabins (oversized, heavy). Their respective container utilization, stowage requirements, and surcharge applicability differ markedly—making granular freight cost modeling essential.
Distinguish between announced initiatives and operational readiness
The launch of ‘Premium Camping Fast Lane’ slots by Chinese ports is confirmed; however, the report does not specify participating carriers, frequency, or guaranteed space allotment. Enterprises should verify actual booking success rates—not just policy announcements—before adjusting lead-time assumptions.
Pre-allocate container slots and revise safety stock thresholds for Q3–Q4 peak season
Given the 22% YoY increase and limited fast-lane capacity, forward buyers should secure bookings earlier than prior-year cycles. Concurrently, safety stock levels for high-turnover items (e.g., premium tent models) may need upward adjustment to offset potential delays—not as speculative hoarding, but as a calibrated buffer aligned with verified transit time extensions.
Editorial Perspective / Industry Observation
Observably, this 22% freight increase is less an isolated cost spike and more a structural signal: maritime bottlenecks are increasingly differentiated by product category, not just volume or geography. Analysis shows that regulatory, environmental, and infrastructural factors now interact to create tiered logistics realities—even within a single end-use segment like outdoor recreation. From an industry perspective, the WTO data reflects an early-stage inflection point where traditional ‘all-cargo’ freight benchmarks no longer reliably inform decision-making for vertically specialized exports. It is currently best understood as a directional warning—not yet a settled equilibrium—requiring continuous validation against real-time port performance metrics and carrier contract terms.
As of publication, this remains a data-point-driven observation anchored solely in the WTO’s May 18, 2026 report. No further freight index revisions, national trade policy responses, or carrier tariff updates have been publicly confirmed beyond the scope of the cited document.
Conclusion: This freight development underscores how macro-logistics disruptions now propagate with category-specific intensity—particularly for value-dense, dimensionally sensitive outdoor equipment. It does not indicate systemic collapse in maritime capacity, nor does it imply uniform impact across all camping-related goods. Rather, it highlights a growing need for granularity in cost modeling, proactive slot management, and evidence-based interpretation of trade outlooks. Currently, it is most accurately understood as a timely input for tactical recalibration—not a strategic pivot point.
Source: World Trade Organization (WTO), 2026 Second Quarter Global Trade Outlook, released May 18, 2026.
Note: Ongoing monitoring is advised for subsequent WTO updates, regional port authority bulletins, and carrier-specific tariff notices—none of which are included in the original report.Recommended News
 Sep 21, 2026What Do Eco-Lodging Standards Cost, From Certification Fees to Compliance Upgrades?Eco lodging standards cost explained: compare certification fees, compliance upgrades, documentation, and operational investments to budget smarter and avoid costly rework.
 Aug 30, 2026How to Choose Marine-Grade Camping Equipment for Saltwater and Coastal ConditionsMarine grade camping equipment guide for coastal trips: compare salt-resistant materials, wind-ready shelters, protected electronics, and maintenance tips for reliable adventures.
 Aug 01, 2026Technical Procurement for Camping Gear: How to Evaluate Specs, Durability, and Supplier FitTechnical procurement for camping gear starts with the real use case. Learn how to assess specs, durability, test reports, and supplier fit to reduce risk and improve ROI.
 Jul 14, 2026SABER V3.2 Adds Carbon Footprint Filing for Premium CampingSABER V3.2 adds carbon footprint filing for Premium Camping in Saudi Arabia. Learn the ISO 14067 PCoC rule, key dates, supplier impact, and how to avoid compliance delays.
 Jul 10, 2026Europe Brings Forward Q3 Premium Camping OrdersEurope Brings Forward Q3 Premium Camping Orders: European retailers moved premium camping procurement deadlines nearly a month earlier. See affected categories, supplier lead-time risks, and FOB cost checks now.
 Jul 10, 2026How to Choose Corrosion Resistant Hotel Furniture for Coastal and Poolside AreasCorrosion resistant hotel furniture buying guide for coastal and poolside areas: compare materials, finishes, test data, and lifecycle value to choose durable, guest-ready outdoor pieces.
 Jul 04, 2026Scenic Slide Systems Cost Breakdown: What Drives Budget in Park and Resort Projects?Scenic slide systems cost explained for park and resort projects. Discover key budget drivers, hidden risks, and smart ways to compare suppliers before costs escalate.
 Jul 02, 2026How to Choose Anti Mildew Resort Furniture for Coastal and High-Humidity ProjectsAnti mildew resort furniture for coastal and high-humidity projects: learn how to compare materials, drainage, corrosion resistance, and lifecycle value for smarter resort sourcing.
 Jul 01, 2026How to Choose High-Durability Trekking Gear for Mountain Use: Materials, Weight, and Weather ProtectionHigh-durability trekking gear for mountain use: learn how to compare materials, weight, and weather protection to choose safer, longer-lasting gear for demanding trails.
 Jun 30, 2026Vietnam Lifts Import Pause but Adds Blockchain Label CheckVietnam lifts the import pause on premium camping goods, but new blockchain label checks and TV-MARK code rules now shape customs clearance. Learn the compliance risks and next steps.
 Jun 29, 2026Vietnam Halts China Premium Camping Imports Over Label ChecksVietnam Halts China Premium Camping Imports over label checks, disrupting customs clearance for lighting and power products. Learn the compliance risks, shipment impact, and what buyers and exporters should review now.
 Jun 29, 2026Eco Resort Development Cost Breakdown: What Drives Budget from Land to OperationsEco resort development cost explained from land and permits to prefab, utilities, and operations. Discover what really drives budget risk and how to plan smarter before approval.
 Jun 28, 2026Vietnam to Enforce QCVN 101:2026 Camping Lighting LabelsVietnam to Enforce QCVN 101:2026 Camping Lighting Labels from August 1, 2026. Learn labeling, VILAS test report, and compliance risks for LED and solar camping lights.
 Jun 28, 2026How to Choose Durable Camping Stoves for Frequent Outdoor Use and Harsh WeatherDurable camping stoves buying guide: learn how to compare materials, wind performance, fuel systems, and serviceability for reliable cooking in harsh weather and frequent outdoor use.
 Jun 27, 2026Vietnam Expands QCVN 16:2026 to Premium Camping DevicesVietnam QCVN 16:2026 expands to Premium Camping devices from Sept 1, 2026. Learn customs, labeling, certification, and procurement impacts for compliant market access.
 Jun 26, 2026Vietnam Mandates QCVN 16:2026 Labels for Premium Camping ImportsVietnam Mandates QCVN 16:2026 Labels for Premium Camping imports from Oct. 1, 2026. Learn how the new rule impacts customs clearance, compliance, suppliers, and delivery planning.
 Jun 26, 2026Pet Carrier Backpacks: How to Choose the Right Size, Ventilation, and Load SupportPetcarrierbackpacks buying guide: learn how to choose the right size, ventilation, and load support for safer, more comfortable pet travel, commuting, and outdoor use.
 Jun 26, 2026How to Read a Durable Camping Equipment Insulation Rating Before You BuyLearn how to read a durable camping equipment insulation rating before you buy, so you can choose warmer, longer-lasting gear with confidence.
 Jun 25, 2026BITE 2025 Puts Premium Camping Orders in FocusBITE 2025 spotlights premium camping orders as Southeast Asian buyers target tent units and modular bathroom cabins with ISO 21930 and ASEAN green materials compliance in focus.
 Jun 24, 2026Fujia Expands Vietnam Output for Premium CampingFujia Expands Vietnam Output for Premium Camping, investing CNY 378 million to boost localized delivery, ease tariff pressure, and strengthen VAT compliance for global buyers.
 Jun 19, 2026ASX 200 Falls 1% as Premium Camping Faces Supply ShiftPremium Camping demand is shifting as the ASX 200 falls 1%. See how Australian retailers favor certified Chinese camping gear, reshaping sourcing, costs, and payment terms.
 Jun 16, 2026What to Look for in Cat Trees and Towers: Size, Stability, Materials, and Cat Agecattreesandtowers buying guide: learn how to compare size, stability, materials, and cat age needs to choose a safer, longer-lasting cat tree your pet will actually use.
 Jun 12, 2026Polysilicon Limit-Up Puts Pressure on Solar Camping CostsPolysilicon limit-up is raising solar camping costs fast. See how BOM pressure, quote volatility, and export contract risks could reshape solar tents and premium camping supply chains.
 Jun 06, 2026New China-Laos-Thailand Route Cuts Land Transit 40%New China-Laos-Thailand Route cuts land transit 40%, reduces customs touchpoints, and lowers multimodal costs for exporters, buyers, and logistics teams moving high-value cargo.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.