Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- What Drives System Interoperability Testing Service Costs in Complex Projects?System interoperability testing service cost depends on integration scope, workflows, environments, and assurance needs. Learn how to budget smarter and reduce project risk.
- Project Planning Sourcing Guides: How to Qualify Suppliers Before Work StartsSourcing guides project planning helps teams qualify suppliers before work begins—verify compliance, delivery capacity, financial strength, and sustainability to reduce risk and protect project outcomes.
- Buyer’s Guide to Kinetic Art: Choosing Safe, Durable Pieces for Public SpacesBuyer guides kinetic art for public spaces: learn how to choose safe, durable, low-maintenance installations with reliable engineering, materials, controls, and lifecycle value.
Popular Tags
TerraVista Metrics (TVM)Industry NewsWTO: Premium Camping Gear Shipping Costs Up 22% YoY
auth.Dr. Hideo Tanaka (Outdoor Gear Engineering Lead)Time
Oct 06, 2026Click Count
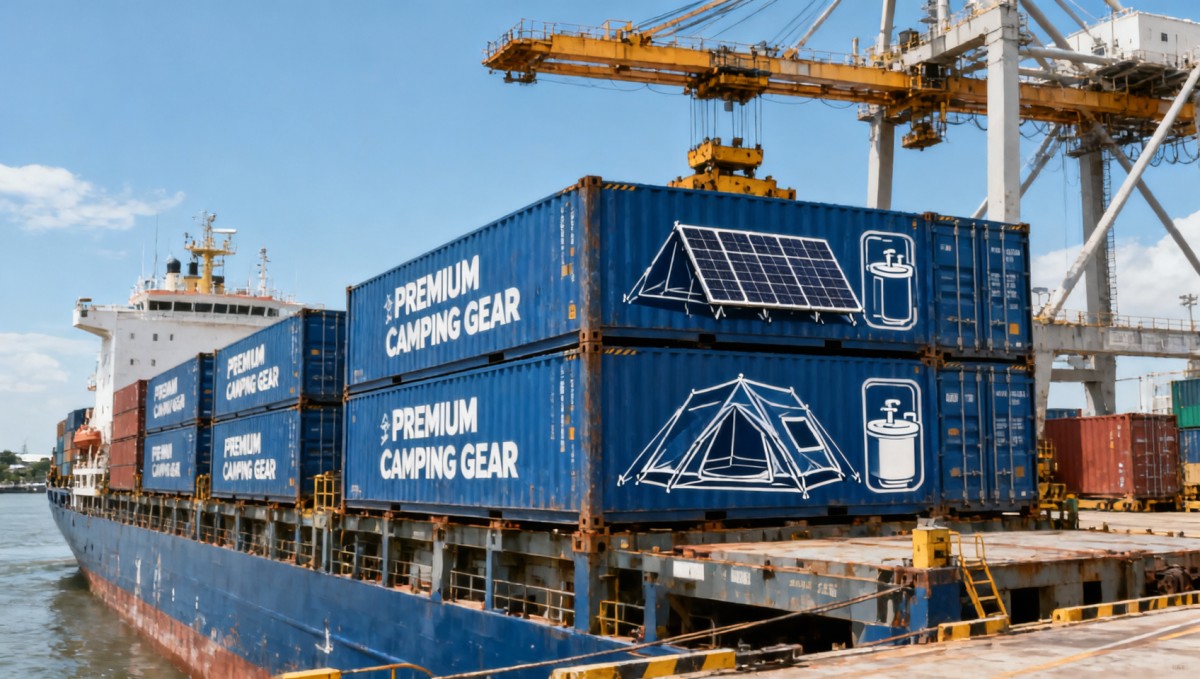
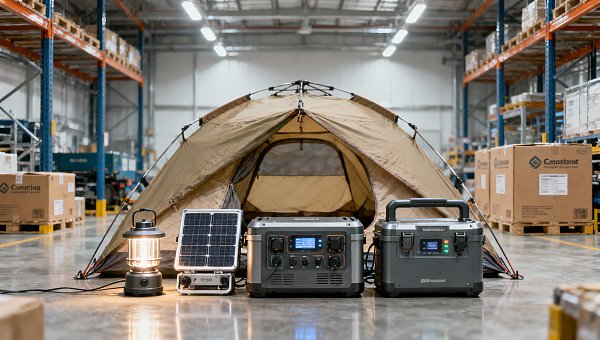
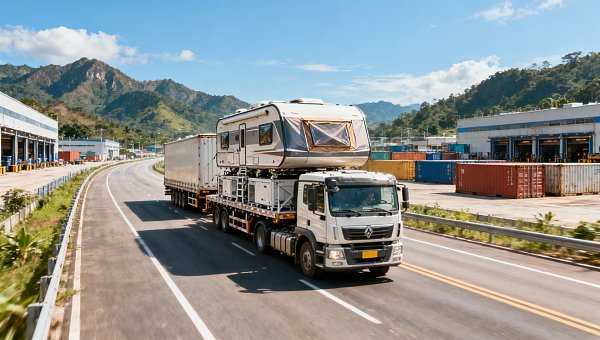
On May 11, 2026, the World Trade Organization (WTO) released its Global Trade Update, reporting a 22% year-on-year increase in maritime freight rates for Premium Camping equipment — including inflatable tents, portable sanitation pods, and solar power kits. The surge stems primarily from prolonged Red Sea rerouting and peak-season congestion at major Southeast Asian ports, with downstream price impacts now visible across European retail channels and procurement strategies.
Event Overview
The WTO’s Global Trade Update (May 11, 2026) confirms that average containerized sea freight costs for Premium Camping equipment rose 22% year-on-year in Q1 2026. This reflects sustained operational disruptions — notably vessel diversions around the Red Sea and intensified port dwell times in Vietnam, Thailand, and Malaysia during the March–April shipping peak. No tariff or regulatory changes were cited as contributing factors; the driver is purely logistical supply-constraint driven.
Industries Affected
Direct Trading Enterprises: Export-oriented distributors and brand-owned importers face compressed margins as freight cost increases are only partially recoverable via end-market pricing. European mid-tier distributors, in particular, report delayed replenishment cycles and reduced order frequency — prompting accelerated shifts toward smaller-batch, faster-turn orders placed directly with Southern Chinese manufacturing hubs.
Raw Material Procurement Firms: Companies sourcing high-performance textiles (e.g., silicone-coated nylon), lithium-based battery cells, or marine-grade aluminum extrusions are experiencing tighter lead times and upward pressure on landed material costs. While raw material unit prices remain stable, added logistics overhead — especially for air-freighted samples or just-in-time components — is raising total acquisition cost per SKU.
Contract Manufacturing & OEM Facilities: Factories in Guangdong and Zhejiang provinces report increased inbound logistics coordination complexity, particularly for imported subassemblies (e.g., German-made regulators, Japanese micro-controllers). At the same time, demand for flexible, low-MOQ production slots has risen by ~17% MoM among EU buyers — straining capacity planning but also creating opportunities for agile, digitally integrated lines.
Supply Chain Service Providers: Freight forwarders, customs brokers, and multimodal integrators are seeing higher inquiry volumes for alternative routing options (e.g., Trans-Pacific via Mexico, rail-sea corridors via Central Asia) and demand for real-time port congestion analytics. However, service-level agreements (SLAs) on transit time reliability have become harder to uphold — increasing contractual risk exposure.
Key Considerations and Response Measures
Reassess Regional Sourcing Footprints
Importers should evaluate nearshoring or regional consolidation — e.g., leveraging bonded logistics parks in Shenzhen or Dongguan — to reduce ocean leg dependency and enable hybrid air-ocean fulfillment for time-sensitive SKUs.
Renegotiate Incoterms with Priority on FCA and DAP
Shifting from FOB to FCA (Free Carrier) at inland consolidation points gives buyers greater control over carrier selection and routing. Similarly, adopting DAP (Delivered at Place) for key EU distribution centers allows more precise landed-cost forecasting amid volatile freight indices.
Integrate Real-Time Freight Index Monitoring into Procurement Workflows
Teams should embed dynamic benchmarks — such as the Drewry World Container Index (WCI) and Xeneta’s Spot Rate Dashboard — into ERP-triggered reorder logic, enabling automatic MOQ or lead-time adjustments when spot rates exceed predefined thresholds.
Editorial Insight / Industry Observation
Observably, the 22% freight hike is not merely a cost shock but a structural signal: global premium outdoor gear trade is entering a phase where logistics resilience outweighs pure cost arbitrage. Analysis shows that companies investing in dual-sourcing networks (e.g., parallel production in Vietnam and Guangdong) and modular packaging designs (to improve TEU utilization) are absorbing cost pressure more effectively than those relying solely on scale-driven offshore manufacturing. Current volatility is better understood not as a temporary disruption, but as an inflection point accelerating supply chain localization — especially for high-value, low-volume camping systems.
Conclusion
This freight surge underscores a broader recalibration in how value is defined across the outdoor recreation supply chain: speed, visibility, and flexibility are increasingly non-negotiable attributes — even at modest cost premiums. For stakeholders, the strategic takeaway is clear — adaptability in routing, responsiveness in order structuring, and transparency in cost modeling are now core operational competencies, not optional enhancements.
Source Attribution
Source: World Trade Organization, Global Trade Update, May 11, 2026 (Publication No. WTO/GTD/2026/3). Data covers Q1 2026 containerized maritime rates for HS codes 9405.50 (portable lighting), 9403.20 (inflatable structures), and 8501.61 (solar power generation sets). Note: WTO indicates continued monitoring of Suez Canal reopening timelines and ASEAN port labor negotiations — both flagged as potential inflection points for Q2 2026 rate trajectories.
Recommended News
 Sep 21, 2026What Do Eco-Lodging Standards Cost, From Certification Fees to Compliance Upgrades?Eco lodging standards cost explained: compare certification fees, compliance upgrades, documentation, and operational investments to budget smarter and avoid costly rework.
 Aug 30, 2026How to Choose Marine-Grade Camping Equipment for Saltwater and Coastal ConditionsMarine grade camping equipment guide for coastal trips: compare salt-resistant materials, wind-ready shelters, protected electronics, and maintenance tips for reliable adventures.
 Aug 01, 2026Technical Procurement for Camping Gear: How to Evaluate Specs, Durability, and Supplier FitTechnical procurement for camping gear starts with the real use case. Learn how to assess specs, durability, test reports, and supplier fit to reduce risk and improve ROI.
 Jul 14, 2026SABER V3.2 Adds Carbon Footprint Filing for Premium CampingSABER V3.2 adds carbon footprint filing for Premium Camping in Saudi Arabia. Learn the ISO 14067 PCoC rule, key dates, supplier impact, and how to avoid compliance delays.
 Jul 10, 2026Europe Brings Forward Q3 Premium Camping OrdersEurope Brings Forward Q3 Premium Camping Orders: European retailers moved premium camping procurement deadlines nearly a month earlier. See affected categories, supplier lead-time risks, and FOB cost checks now.
 Jul 10, 2026How to Choose Corrosion Resistant Hotel Furniture for Coastal and Poolside AreasCorrosion resistant hotel furniture buying guide for coastal and poolside areas: compare materials, finishes, test data, and lifecycle value to choose durable, guest-ready outdoor pieces.
 Jul 04, 2026Scenic Slide Systems Cost Breakdown: What Drives Budget in Park and Resort Projects?Scenic slide systems cost explained for park and resort projects. Discover key budget drivers, hidden risks, and smart ways to compare suppliers before costs escalate.
 Jul 02, 2026How to Choose Anti Mildew Resort Furniture for Coastal and High-Humidity ProjectsAnti mildew resort furniture for coastal and high-humidity projects: learn how to compare materials, drainage, corrosion resistance, and lifecycle value for smarter resort sourcing.
 Jul 01, 2026How to Choose High-Durability Trekking Gear for Mountain Use: Materials, Weight, and Weather ProtectionHigh-durability trekking gear for mountain use: learn how to compare materials, weight, and weather protection to choose safer, longer-lasting gear for demanding trails.
 Jun 30, 2026Vietnam Lifts Import Pause but Adds Blockchain Label CheckVietnam lifts the import pause on premium camping goods, but new blockchain label checks and TV-MARK code rules now shape customs clearance. Learn the compliance risks and next steps.
 Jun 29, 2026Vietnam Halts China Premium Camping Imports Over Label ChecksVietnam Halts China Premium Camping Imports over label checks, disrupting customs clearance for lighting and power products. Learn the compliance risks, shipment impact, and what buyers and exporters should review now.
 Jun 29, 2026Eco Resort Development Cost Breakdown: What Drives Budget from Land to OperationsEco resort development cost explained from land and permits to prefab, utilities, and operations. Discover what really drives budget risk and how to plan smarter before approval.
 Jun 28, 2026Vietnam to Enforce QCVN 101:2026 Camping Lighting LabelsVietnam to Enforce QCVN 101:2026 Camping Lighting Labels from August 1, 2026. Learn labeling, VILAS test report, and compliance risks for LED and solar camping lights.
 Jun 28, 2026How to Choose Durable Camping Stoves for Frequent Outdoor Use and Harsh WeatherDurable camping stoves buying guide: learn how to compare materials, wind performance, fuel systems, and serviceability for reliable cooking in harsh weather and frequent outdoor use.
 Jun 27, 2026Vietnam Expands QCVN 16:2026 to Premium Camping DevicesVietnam QCVN 16:2026 expands to Premium Camping devices from Sept 1, 2026. Learn customs, labeling, certification, and procurement impacts for compliant market access.
 Jun 26, 2026Vietnam Mandates QCVN 16:2026 Labels for Premium Camping ImportsVietnam Mandates QCVN 16:2026 Labels for Premium Camping imports from Oct. 1, 2026. Learn how the new rule impacts customs clearance, compliance, suppliers, and delivery planning.
 Jun 26, 2026Pet Carrier Backpacks: How to Choose the Right Size, Ventilation, and Load SupportPetcarrierbackpacks buying guide: learn how to choose the right size, ventilation, and load support for safer, more comfortable pet travel, commuting, and outdoor use.
 Jun 26, 2026How to Read a Durable Camping Equipment Insulation Rating Before You BuyLearn how to read a durable camping equipment insulation rating before you buy, so you can choose warmer, longer-lasting gear with confidence.
 Jun 25, 2026BITE 2025 Puts Premium Camping Orders in FocusBITE 2025 spotlights premium camping orders as Southeast Asian buyers target tent units and modular bathroom cabins with ISO 21930 and ASEAN green materials compliance in focus.
 Jun 24, 2026Fujia Expands Vietnam Output for Premium CampingFujia Expands Vietnam Output for Premium Camping, investing CNY 378 million to boost localized delivery, ease tariff pressure, and strengthen VAT compliance for global buyers.
 Jun 19, 2026ASX 200 Falls 1% as Premium Camping Faces Supply ShiftPremium Camping demand is shifting as the ASX 200 falls 1%. See how Australian retailers favor certified Chinese camping gear, reshaping sourcing, costs, and payment terms.
 Jun 16, 2026What to Look for in Cat Trees and Towers: Size, Stability, Materials, and Cat Agecattreesandtowers buying guide: learn how to compare size, stability, materials, and cat age needs to choose a safer, longer-lasting cat tree your pet will actually use.
 Jun 12, 2026Polysilicon Limit-Up Puts Pressure on Solar Camping CostsPolysilicon limit-up is raising solar camping costs fast. See how BOM pressure, quote volatility, and export contract risks could reshape solar tents and premium camping supply chains.
 Jun 06, 2026New China-Laos-Thailand Route Cuts Land Transit 40%New China-Laos-Thailand Route cuts land transit 40%, reduces customs touchpoints, and lowers multimodal costs for exporters, buyers, and logistics teams moving high-value cargo.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.