Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- Hotel Security Protocols: A Compliance Checklist for Protecting Guests and StaffSecurity protocols for hospitality: use this practical hotel compliance checklist to protect guests, staff, data, access points, and emergency operations.
- How to Evaluate Resort Slide System Suppliers for Safety, Capacity, and Project SupportResort slide systems supplier evaluation guide: compare safety evidence, real capacity, durable materials, and project support for confident resort investments.
- Sustainable Building Materials Pricing: How Buyers Compare Cost, Life Cycle, and RiskSustainable building materials pricing explained: compare installed cost, life-cycle value, carbon evidence, and supply-chain risk for smarter procurement decisions.
Popular Tags
TerraVista Metrics (TVM)Industry NewsRV Chip Lead Times Extend to 26 Weeks
auth.Dr. Hideo Tanaka (Outdoor Gear Engineering Lead)Time
Sep 09, 2026Click Count
The timing of this development is not explicitly stated in the available information, but the reported extension in lead times for key chips used in RV Components points to a practical shift in supply allocation rules rather than a routine delivery fluctuation. For manufacturers, buyers, and supply-chain coordinators involved in intelligent temperature control, battery management, and onboard gateway products, the issue is worth close attention because capacity reallocation at the foundry level can quickly affect procurement scheduling, component substitution reviews, delivery commitments, and related compliance documentation.
What the reported supply change confirms
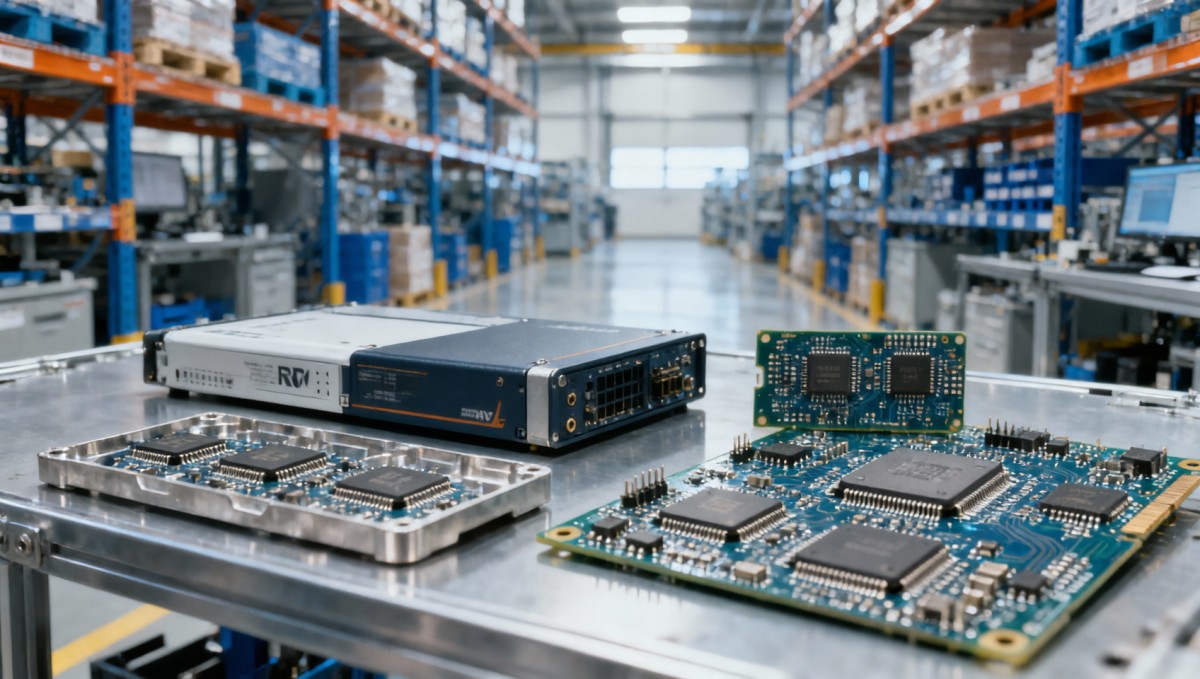
According to a TechInsights supply-chain report dated June 5, 2026, MCU products used in RV Components, including the NXP S32K series, and power management ICs such as TI TPS6598x are facing a second round of capacity reallocation. The report states that TSMC's Nanjing facility has shifted part of its 8-inch capacity toward automotive-grade IGBT production.
As a direct result of that adjustment, the average lead time for the above chip categories has extended from 14 weeks to 26 weeks. The same information also indicates that Chinese RV component manufacturers have already started secondary supplier substitution validation.
Where the pressure is likely to appear first
Procurement and sourcing teams face tighter qualification constraints
From an industry perspective, procurement teams are likely to feel the impact first because the reported change affects chips tied to control and power functions rather than low-risk general parts. In practice, this means buyers may need to pay closer attention to approved vendor lists, technical equivalence checks, delivery clauses, and document consistency when evaluating replacement sources.
What deserves closer attention is that any substitution process in these component categories can also trigger renewed review of specifications, bill-of-material alignment, and internal approval records. Even where alternative supply is available, the commercial decision may depend on whether technical and compliance files can be updated in time for shipment and customer acceptance.
Manufacturing schedules may be affected through validation, not only shortage
For RV component manufacturers, the immediate issue is not only longer chip lead times but also the operational burden created by secondary supplier validation. Where chips are linked to temperature control, battery management, or onboard gateway functions, production planning may need to account for engineering review cycles, sample verification, and possible documentation updates before alternative parts can enter formal use.
Analysis shows that this kind of pressure can move from purchasing into manufacturing execution quickly, especially when delivery commitments rely on pre-approved configurations. Companies in this position should therefore watch for changes in internal release procedures, customer-side technical acceptance requirements, and any contract terms tied to part consistency.
Delivery, after-sales, and traceability functions may need closer control
Channel operators, integrators, and after-sales teams may also be affected if longer lead times lead to phased deliveries, model adjustments, or part substitutions. In such cases, the key business concern is less about headline availability and more about whether product records, service documentation, and traceability files remain consistent across batches.
Observably, if substitution validation expands, downstream participants may need clearer control over version records, incoming inspection references, and service-part identification. That is a practical compliance issue even when no new formal regulation has been announced in the input information.
What companies should monitor now
Track whether substitution requires new compliance review
Analysis shows that companies should first determine whether secondary supplier replacement affects existing certification files, test references, technical descriptions, or customer submission documents. The available information does not confirm any mandatory new certification outcome, so this should be treated as a live review point rather than an established requirement.
Recheck procurement terms and delivery commitments
Businesses with forward delivery obligations should review whether current procurement plans still match the reported 26-week average lead time. What deserves closer attention is whether purchase agreements, scheduling assumptions, and delivery notices need adjustment to reflect a materially longer replenishment cycle.
Watch technical document alignment in bids and customer files
If manufacturers move toward alternative chip sources, they should monitor whether technical bid documents, product specifications, and customer-facing materials continue to match actual shipped configurations. This is especially relevant where chips are embedded in control-related functions and where part-number consistency may matter in project review or acceptance procedures.
Follow further signals from the supply and execution side
The current information confirms a supply-chain adjustment and an ongoing supplier-validation response, but it does not provide full execution detail. Companies should therefore continue watching for follow-up statements, customer qualification positions, and any changes in practical review standards used in procurement or acceptance.
Why this matters beyond a single delivery delay
Observably, this development is better understood as an execution signal within the supply and compliance chain than as an isolated logistics issue. The reported capacity shift toward automotive-grade IGBT production suggests that allocation priorities at the manufacturing level can reshape access conditions for adjacent industrial component users, even without a newly published regulation in the input material.
From an industry perspective, the most important point is that supply pressure in control-related semiconductors often translates into rule-sensitive business decisions: which suppliers remain qualified, which documents need revision, and which delivery commitments remain realistic. For that reason, the event should be watched not only as a sourcing issue but also as a trigger for process discipline across validation, procurement, and shipment control.
How the market should read the latest signal
At this stage, it is more appropriate to understand the development as a confirmed supply-side change with practical rule implications, rather than as a fully settled new market order. The extension from 14 weeks to 26 weeks is already a concrete operational signal, while the wider impact on qualification practice, customer acceptance, and delivery execution still requires continued observation.
A rational reading is that companies connected to RV Components should prepare for stricter internal coordination around approved parts, substitution evidence, and delivery planning. The available facts support caution and monitoring, but they do not support broader conclusions beyond the reported supply shift and validation response.
Basis of this article and points still to verify
This article is generated based on the user-provided news title, event timing, and event summary. The specific official source link was not provided in the input, so further verification remains necessary. For events of this type, relevant source categories may usually include official announcements, regulator releases, customs or trade authority information, industry association updates, standard-setting documents, and reporting by authoritative media.
Further observation is still needed on any later clarification affecting implementation details, certification interpretation, bid-document changes, industry feedback, and how companies carry out supplier substitution and delivery adjustment in practice.
Recommended News
 Aug 14, 2026Indonesia’s Nickel Export Buffer Policy Could Ease RV and Yacht Tech Supply ChainsIndonesia’s nickel export buffer policy may ease RV and yacht tech supply chains, helping stabilize battery, steel, and sourcing costs.
 Jul 13, 2026West Coast Port Strike Pauses, RV Lead Time Stays at 52 DaysWest Coast port strike pauses, but RV lead time stays at 52 days. See how congestion, tight booking windows, and 40HQ premiums are impacting exporters and distributors.
 Jul 11, 2026RV Component Freight Jumps 32%, Q3 Lead Times SlipRV component freight jumps 32% as Q3 lead times slip from 8 to 14–16 weeks. See how Red Sea disruption, port strikes, and precision-part gaps may impact sourcing, costs, and delivery plans.
 Jul 09, 2026RV Aluminum Prices Jump 12% as Port Delays DeepenRV aluminum prices jump 12% as port delays deepen, pushing 6061-T6 costs to $3,820/ton. See how RV OEMs, buyers, and suppliers can respond to rising costs and slower deliveries.
 Jul 06, 2026Camper Van Components in Europe: How to Compare Standards, Fit, and Supply OptionsCamper van components Europe guide for buyers: compare compliance, fit, durability, and supply options to reduce risk, improve sourcing decisions, and protect margins.
 Jun 30, 2026CPSC Recall Expansion Raises RV Brake Compliance BarCPSC recall expansion raises RV brake compliance bar as importers demand ISO 26262 ASIL-B validation. See how OEMs, buyers, and suppliers can reduce risk and protect orders.
 Jun 27, 2026CPSC Tightens RV Component Rules With UL 2871:2026CPSC Tightens RV Component Rules With UL 2871:2026: learn how new U.S. import, labeling, and certification rules affect RV batteries, BMS controllers, and DC modules from August 2026.
 Jun 24, 2026U.S. 301 Review May Lift RV Component Tariffs to 25%RV Components face possible U.S. 301 tariffs up to 25%, with a tight July 24 shipping window. Learn how exporters and buyers can protect pricing, compliance, and Q3 supply plans.
 Jun 23, 2026Export Controls Raise RV Chip Supply RiskExport controls raise RV chip supply risk as FPGA and ADC/DAC lead times exceed 26 weeks. Learn how RV controller makers can manage sourcing, compliance, substitution, and delivery pressure.
 Jun 23, 2026Screwdrivers Set Buying Guide: Types, Bit Materials, and What to Check Before PurchaseScrewdriversset buying guide: compare types, bit materials, handle comfort, and key pre-purchase checks to choose a durable set that saves time, money, and repair frustration.
 Jun 22, 2026RV Components Lead Times Stretch to 18 WeeksRV Components lead times stretch to 18 weeks as port disruption and aluminum export limits tighten supply. See what OEMs, buyers, and logistics teams should monitor now.
 Jun 21, 2026RV Parts Lead Times Stretch to 18 Weeks After Port StrikeRV parts lead times stretch to 18 weeks after the LA/Long Beach port strike. Learn how RV OEMs, importers, and suppliers can respond to booking suspensions and sourcing pressure.
 Jun 20, 2026India Issues Final AD Ruling on China TPU Paint Protection FilmIndia Issues Final AD Ruling on China TPU Paint Protection Film—learn how the anti-dumping decision may impact TPU sourcing, pricing, and supply chain planning across India and export-linked markets.
 Jun 18, 2026Vietnam Eases RV Components Clearance for China SuppliersVietnam eases RV components clearance for China suppliers, allowing eligible shipments to use CNAS-recognized test reports and ISO 9001 for faster 7–10 day customs delivery.
 Jun 17, 2026Vietnam Expands RV Component Certification ExemptionsVietnam Expands RV Component Certification Exemptions: learn how the new self-declaration and type-test filing rules can cut import delays, reduce compliance costs, and reshape OEM sourcing strategy.
 Jun 16, 2026UL 9741-2026 Sets Dual-Loop BMS Rule for RV Lithium ComponentsUL 9741-2026 sets a dual-loop BMS rule for RV lithium components, requiring thermal runaway warning and physical cutoff by Dec 1, 2026. Learn the compliance impact now.
 Jun 15, 2026UL Tightens RV Lithium Battery Rules for U.S. MarketUL Tightens RV Lithium Battery Rules for U.S. Market: learn how UL 9741-2026 BMS dual-circuit redundancy requirements may impact RV battery exports, compliance timelines, and supplier planning.
 Jun 14, 2026CPSC Mandates UL 9741 for RV BMS ModulesCPSC mandates UL 9741 for RV BMS modules made after Sept. 1, 2026. Learn the 87-day compliance deadline, supply chain impact, and key actions for U.S.-bound RV components.
 Jun 13, 2026CPSC Sets UL 9741 Deadline for RV Lithium ModulesCPSC sets a UL 9741 deadline for RV lithium modules by Dec. 1, 2026. Learn how BMS, OTA security audits, and thermal runaway testing could impact U.S. market access.
 Jun 11, 2026RV Control MCU Lead Times Stretch to 26 WeeksRV Control MCU lead times stretch to 26 weeks, raising sourcing risks for manufacturers and buyers. Explore qualified domestic alternatives, compliance milestones, and smarter supply-chain planning.
 Jun 11, 2026Resistor Spark Plugs vs Standard Plugs: What’s the Difference and When to Use EachResistor spark plugs vs standard plugs: learn the key differences, when to use each, and how the right choice improves reliability, electronics compatibility, and maintenance confidence.
 Jun 10, 2026RV MCU Lead Times Stretch to 26 Weeks as China Alternatives AdvanceRV MCU lead times stretch to 26 weeks as China alternatives advance. Discover supply risks, qualification progress, and what RV electronics buyers should monitor now.
 Jun 10, 2026How to Choose Vehicle Electronics for RV Upgrades: Power, Compatibility, and SafetyVehicle electronics for RV upgrades: learn how to evaluate power demands, compatibility, and safety to choose reliable systems, reduce failures, and improve long-term performance.
 Jun 09, 2026RV MCU Lead Times Stretch as Local Supply Gains Audit AccessRV MCU lead times stretch beyond 26 weeks as local suppliers gain audit access and certification progress. Explore sourcing risks, compliance checks, and qualified alternatives for RV supply chains.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.