Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- What Engineering Performance Testing Should Cover During a Specification ReviewEngineering performance testing for specification review: learn how to verify structural strength, durability, safety, sustainability, and system reliability before costly project decisions.
- Planning Recreational Cable Transport Networks for Resorts and Mountain ParksExplore recreational cable transport networks for resorts and mountain parks, with expert planning insights on capacity, terrain, safety, station design, and long-term performance.
- How to Plan Theme Park Infrastructure for Mixed-Use DevelopmentsTheme park infrastructure for mixed use developments: plan resilient utilities, circulation, attractions, hospitality, and digital systems for scalable destinations.
Popular Tags
TerraVista Metrics (TVM)Industry NewsRV Components Lead Times Stretch to 18 Weeks
auth.Dr. Hideo Tanaka (Outdoor Gear Engineering Lead)Time
Sep 03, 2026Click Count
The timing of the underlying disruption was not clearly specified in the source material, but an ALI supply chain alert dated June 22, 2026 indicates that global lead times for key RV Components have extended to 18 weeks. For North American OEMs, procurement teams, and supply chain service providers, this matters because the change reflects pressure from both port-side labor disruption on the U.S. West Coast and tighter export availability for aluminum profiles, directly affecting delivery planning for critical RV production inputs.

What the latest supply chain alert confirms
According to the latest supply chain warning issued by the American Logistics Institute (ALI) on June 22, 2026, the average delivery cycle for key RV Components has risen to 18 weeks, which is 5.5 weeks longer than at the beginning of 2026. The confirmed drivers cited in the alert are the ongoing strikes at the Los Angeles and Long Beach ports and China’s quarterly quota management for aluminum profile exports.
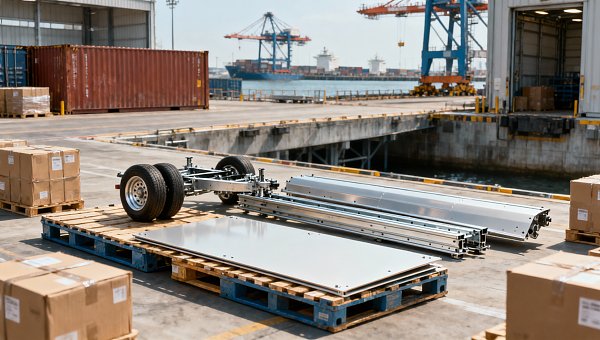
The components specifically referenced include axles, slide-out rails, and lightweight body panels. The same alert also states that North American OEM manufacturers are urgently initiating reviews of second-tier suppliers in China, with priority given to composite suppliers capable of serving both Modular Cabins and RV Components while also offering localized warehousing and fast response capacity.
Where the pressure is likely to show up first
Production scheduling faces more uncertainty
From an industry perspective, OEM manufacturers and assembly planners are among the first groups likely to feel the impact because the affected parts are tied to core vehicle structure and functionality. If lead times remain extended, the main pressure point is likely to be production sequencing, especially where axles, slide-out systems, and lightweight body materials must arrive in coordination.
Procurement teams need to watch supplier depth
For sourcing and purchasing teams, the development points to a more immediate need to assess supplier redundancy rather than relying only on existing approved vendors. What deserves closer attention is whether second-tier suppliers can meet qualification, documentation, warehousing, and response expectations quickly enough to support active programs.
Logistics providers may face tighter execution windows
Supply chain service providers may also be affected because the reported disruption combines upstream export constraints with downstream port delays. In practice, the pressure is likely to center on shipment timing, inventory positioning, and communication accuracy across cross-border deliveries.
What companies should monitor now
Changes in official wording and operating rules
Analysis shows that companies should closely track any follow-up wording related to port disruptions and quarterly aluminum profile export quota management. The business impact depends not only on the existence of these constraints, but also on how they are implemented in actual shipment release and fulfillment processes.
Exposure in priority component categories
Companies with purchasing exposure to axles, slide-out rails, and lightweight body panels should review whether these categories have become bottlenecks in current delivery commitments. The practical question is not only whether supply exists, but whether it can move on time under current constraints.
Supplier qualification speed versus fulfillment ability
The urgent review of second-tier Chinese suppliers suggests that qualification speed is becoming a commercial factor. Observably, buyers are not only looking at price or base manufacturing capacity, but also at localized warehousing and fast-response capability, especially for suppliers positioned across both Modular Cabins and RV Components.
Customer communication and contingency planning
For commercial and account teams, it is important to align delivery expectations with customers early. Analysis shows that longer lead times can quickly become a contract execution issue if schedule changes are not reflected in procurement plans, internal forecasts, and external communication.
Why this looks bigger than a short shipping delay
Observably, this development should not be read only as an isolated logistics slowdown. It is more appropriate to understand this as a combined supply chain signal: transport disruption and material-related export control are affecting the same product chain at the same time. That does not yet prove a long-term structural shift, but it does indicate that supplier resilience, warehousing location, and response speed are moving closer to the center of OEM purchasing decisions.
From an industry perspective, the most important point is that North American OEMs are already reacting by expanding supplier review activity. That suggests the market is not treating the issue as purely temporary friction, even though the full duration and scope still require continued observation.
How this development is best understood for now
At this stage, the reported extension of RV Components lead times to 18 weeks is best understood as a meaningful operating signal rather than a final industry outcome. The confirmed facts point to immediate strain in procurement and delivery coordination, while the broader implications for sourcing structure and supplier selection still need to be monitored with caution.
A balanced reading is that the situation has already become relevant for day-to-day execution, especially for OEMs and suppliers linked to key structural RV parts. Whether it remains a short-cycle disruption or develops into a longer sourcing realignment depends on how the cited port and export constraints evolve.
Basis of this article and what still needs verification
This article is based on the user-provided news title, event timing note, and event summary. The specific official source link was not provided in the input, so further verification remains necessary. For this type of industry update, commonly relevant source categories include official notices, company statements, industry association alerts, authoritative media reporting, and standards or trade-related documents.
What still needs continued checking includes whether there are further updates to the port disruption, any adjustment in quarterly export quota implementation, and whether OEM supplier review activity translates into broader changes in approved sourcing structures.
Recommended News
 Aug 14, 2026Indonesia’s Nickel Export Buffer Policy Could Ease RV and Yacht Tech Supply ChainsIndonesia’s nickel export buffer policy may ease RV and yacht tech supply chains, helping stabilize battery, steel, and sourcing costs.
 Jul 13, 2026West Coast Port Strike Pauses, RV Lead Time Stays at 52 DaysWest Coast port strike pauses, but RV lead time stays at 52 days. See how congestion, tight booking windows, and 40HQ premiums are impacting exporters and distributors.
 Jul 11, 2026RV Component Freight Jumps 32%, Q3 Lead Times SlipRV component freight jumps 32% as Q3 lead times slip from 8 to 14–16 weeks. See how Red Sea disruption, port strikes, and precision-part gaps may impact sourcing, costs, and delivery plans.
 Jul 09, 2026RV Aluminum Prices Jump 12% as Port Delays DeepenRV aluminum prices jump 12% as port delays deepen, pushing 6061-T6 costs to $3,820/ton. See how RV OEMs, buyers, and suppliers can respond to rising costs and slower deliveries.
 Jul 06, 2026Camper Van Components in Europe: How to Compare Standards, Fit, and Supply OptionsCamper van components Europe guide for buyers: compare compliance, fit, durability, and supply options to reduce risk, improve sourcing decisions, and protect margins.
 Jun 30, 2026CPSC Recall Expansion Raises RV Brake Compliance BarCPSC recall expansion raises RV brake compliance bar as importers demand ISO 26262 ASIL-B validation. See how OEMs, buyers, and suppliers can reduce risk and protect orders.
 Jun 27, 2026CPSC Tightens RV Component Rules With UL 2871:2026CPSC Tightens RV Component Rules With UL 2871:2026: learn how new U.S. import, labeling, and certification rules affect RV batteries, BMS controllers, and DC modules from August 2026.
 Jun 24, 2026U.S. 301 Review May Lift RV Component Tariffs to 25%RV Components face possible U.S. 301 tariffs up to 25%, with a tight July 24 shipping window. Learn how exporters and buyers can protect pricing, compliance, and Q3 supply plans.
 Jun 23, 2026Export Controls Raise RV Chip Supply RiskExport controls raise RV chip supply risk as FPGA and ADC/DAC lead times exceed 26 weeks. Learn how RV controller makers can manage sourcing, compliance, substitution, and delivery pressure.
 Jun 23, 2026Screwdrivers Set Buying Guide: Types, Bit Materials, and What to Check Before PurchaseScrewdriversset buying guide: compare types, bit materials, handle comfort, and key pre-purchase checks to choose a durable set that saves time, money, and repair frustration.
 Jun 22, 2026RV Components Lead Times Stretch to 18 WeeksRV Components lead times stretch to 18 weeks as port disruption and aluminum export limits tighten supply. See what OEMs, buyers, and logistics teams should monitor now.
 Jun 21, 2026RV Parts Lead Times Stretch to 18 Weeks After Port StrikeRV parts lead times stretch to 18 weeks after the LA/Long Beach port strike. Learn how RV OEMs, importers, and suppliers can respond to booking suspensions and sourcing pressure.
 Jun 20, 2026India Issues Final AD Ruling on China TPU Paint Protection FilmIndia Issues Final AD Ruling on China TPU Paint Protection Film—learn how the anti-dumping decision may impact TPU sourcing, pricing, and supply chain planning across India and export-linked markets.
 Jun 18, 2026Vietnam Eases RV Components Clearance for China SuppliersVietnam eases RV components clearance for China suppliers, allowing eligible shipments to use CNAS-recognized test reports and ISO 9001 for faster 7–10 day customs delivery.
 Jun 17, 2026Vietnam Expands RV Component Certification ExemptionsVietnam Expands RV Component Certification Exemptions: learn how the new self-declaration and type-test filing rules can cut import delays, reduce compliance costs, and reshape OEM sourcing strategy.
 Jun 16, 2026UL 9741-2026 Sets Dual-Loop BMS Rule for RV Lithium ComponentsUL 9741-2026 sets a dual-loop BMS rule for RV lithium components, requiring thermal runaway warning and physical cutoff by Dec 1, 2026. Learn the compliance impact now.
 Jun 15, 2026UL Tightens RV Lithium Battery Rules for U.S. MarketUL Tightens RV Lithium Battery Rules for U.S. Market: learn how UL 9741-2026 BMS dual-circuit redundancy requirements may impact RV battery exports, compliance timelines, and supplier planning.
 Jun 14, 2026CPSC Mandates UL 9741 for RV BMS ModulesCPSC mandates UL 9741 for RV BMS modules made after Sept. 1, 2026. Learn the 87-day compliance deadline, supply chain impact, and key actions for U.S.-bound RV components.
 Jun 13, 2026CPSC Sets UL 9741 Deadline for RV Lithium ModulesCPSC sets a UL 9741 deadline for RV lithium modules by Dec. 1, 2026. Learn how BMS, OTA security audits, and thermal runaway testing could impact U.S. market access.
 Jun 11, 2026RV Control MCU Lead Times Stretch to 26 WeeksRV Control MCU lead times stretch to 26 weeks, raising sourcing risks for manufacturers and buyers. Explore qualified domestic alternatives, compliance milestones, and smarter supply-chain planning.
 Jun 11, 2026Resistor Spark Plugs vs Standard Plugs: What’s the Difference and When to Use EachResistor spark plugs vs standard plugs: learn the key differences, when to use each, and how the right choice improves reliability, electronics compatibility, and maintenance confidence.
 Jun 10, 2026RV MCU Lead Times Stretch to 26 Weeks as China Alternatives AdvanceRV MCU lead times stretch to 26 weeks as China alternatives advance. Discover supply risks, qualification progress, and what RV electronics buyers should monitor now.
 Jun 10, 2026How to Choose Vehicle Electronics for RV Upgrades: Power, Compatibility, and SafetyVehicle electronics for RV upgrades: learn how to evaluate power demands, compatibility, and safety to choose reliable systems, reduce failures, and improve long-term performance.
 Jun 09, 2026RV MCU Lead Times Stretch as Local Supply Gains Audit AccessRV MCU lead times stretch beyond 26 weeks as local suppliers gain audit access and certification progress. Explore sourcing risks, compliance checks, and qualified alternatives for RV supply chains.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.