Search News
TerraVista Metrics (TVM)Industry Portal
TerraVista Metrics (TVM)Hot Articles
TerraVista Metrics (TVM)- Hotel Security Protocols: A Compliance Checklist for Protecting Guests and StaffSecurity protocols for hospitality: use this practical hotel compliance checklist to protect guests, staff, data, access points, and emergency operations.
- How to Evaluate Resort Slide System Suppliers for Safety, Capacity, and Project SupportResort slide systems supplier evaluation guide: compare safety evidence, real capacity, durable materials, and project support for confident resort investments.
- Sustainable Building Materials Pricing: How Buyers Compare Cost, Life Cycle, and RiskSustainable building materials pricing explained: compare installed cost, life-cycle value, carbon evidence, and supply-chain risk for smarter procurement decisions.
Popular Tags
TerraVista Metrics (TVM)Industry NewsU.S. Copper Tariff Deadline Looms, Tightening Arbitrage Window for RV and Smart Lighting Exports
auth.Time
Sep 09, 2026Click Count
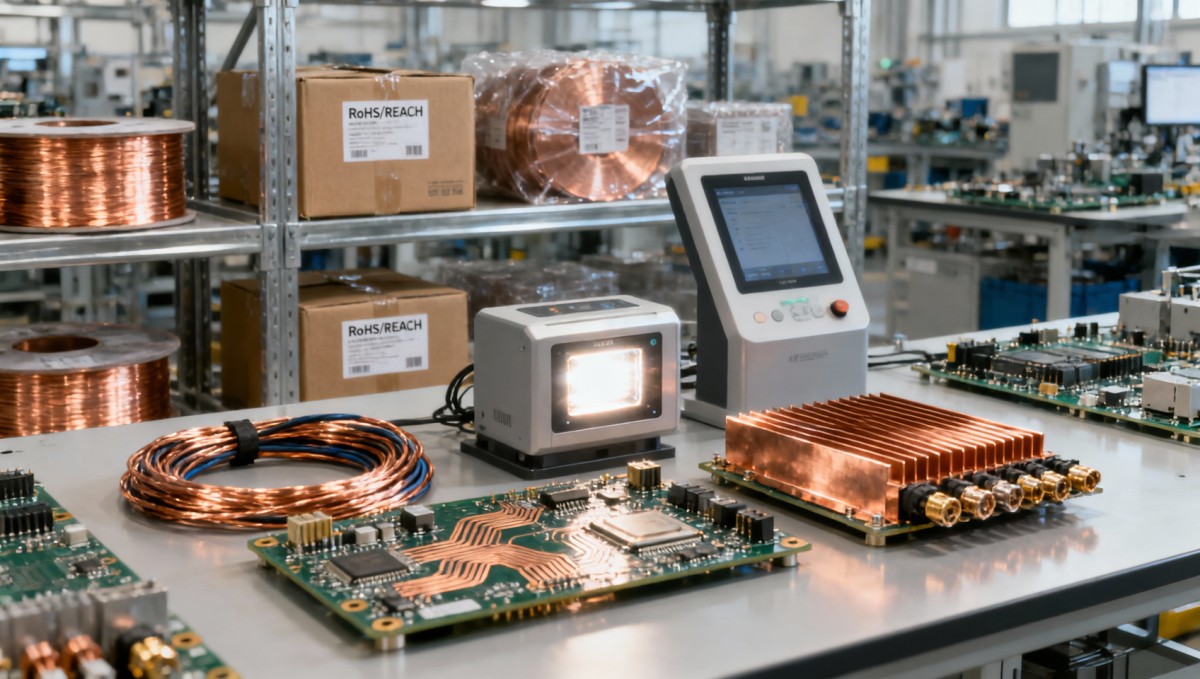
The U.S. final determination on tariffs for refined copper is scheduled for late June — though the exact event date was not specified. This regulatory development is directly affecting exporters of recreational vehicle (RV) components, smart lighting systems, and kiosk technologies, where copper serves as a critical material in printed circuit boards (PCBs), wiring harnesses, and thermal management modules. Heightened tariff uncertainty is prompting importers to accelerate procurement or shift shipments through third-country intermediaries, while documentation requirements and delivery timelines have become markedly stricter.

Confirmed Regulatory Timeline and Market Reaction
The U.S. government’s final ruling on additional duties for refined copper is set for late June. This has triggered a surge in cross-market arbitrage activity. COMEX copper inventories currently represent 44% of total exchange-traded copper stocks globally; including over-the-counter reserves, total accessible copper stock exceeds one million metric tons. Copper remains an essential raw material across RV Components, Smart Lighting, and Kiosk Tech supply chains — particularly in PCBs, cables, and heat dissipation modules. In response to tariff uncertainty, importers are engaging in advance bulk purchasing or rerouting consignments via third-party jurisdictions. Concurrently, customs documentation and delivery schedule compliance requirements have intensified. Chinese suppliers are now required to update their RoHS and REACH declarations specifically for copper alloy compositions and strengthen origin traceability throughout the supply chain.
Impact Across Supply Chain Roles
Direct Exporters
Tariff ambiguity increases landed cost unpredictability and delays order confirmation cycles. Exporters face tighter deadlines for customs documentation submission and greater scrutiny of origin claims — especially for copper-containing subassemblies shipped as finished goods.
Raw Material Procurement Firms
Firms sourcing copper cathodes, rod, or alloy preforms must now assess price volatility, forward contract exposure, and alternative sourcing routes — including non-U.S.-bound inventory allocation strategies to mitigate risk ahead of the June deadline.
Electronics and Enclosure Manufacturers
Manufacturers integrating copper into PCBs, connectors, heatsinks, or housing components must verify updated material declarations with suppliers and ensure traceability data aligns with both REACH Annex XVII and RoHS Directive Annex II requirements — particularly for alloys containing lead, cadmium, or hexavalent chromium impurities.
Supply Chain & Logistics Service Providers
Third-party logistics and trade compliance firms report rising demand for origin verification support, tariff classification advisory services (e.g., HTS code 7403.11–7403.19), and documentation audits — especially for mixed-material assemblies where copper content thresholds trigger regulatory obligations.
Key Compliance and Operational Priorities for Suppliers
Update RoHS/REACH Alloy Composition Disclosures
Chinese suppliers must revise technical dossiers to explicitly declare copper alloy grades, trace element profiles (e.g., Pb, Cd, Cr⁶⁺), and conformity statements aligned with EU Regulation (EC) No 1907/2006 (REACH) and Directive 2011/65/EU (RoHS).
Strengthen Origin Traceability from Smelter to Shipment
End-to-end origin documentation — including smelter identification, purchase invoices, refining certificates, and mill test reports — is now essential to substantiate country-of-origin claims and avoid customs hold-ups or reclassification risks.
Review Delivery Schedules and Contract Clauses
Export contracts should be audited for force majeure, tariff pass-through, and documentation liability clauses. Lead times for copper-intensive components are extending due to upstream inventory hoarding and increased inspection frequency at ports of entry.
Prepare for Third-Country Transit Documentation
Where consignments are routed via intermediary jurisdictions to defer U.S. tariff application, additional proof of ‘substantial transformation’ and commercial invoices reflecting true transaction value must be maintained — subject to CBP audit standards.
Industry Observation: Compliance Burden Is Accelerating Technical Due Diligence
Analysis shows that tariff-driven uncertainty is shifting compliance emphasis from end-product certification to granular material-level accountability. What deserves closer attention is how rapidly REACH and RoHS verification expectations are converging with trade compliance workflows — particularly for multi-tiered electronics supply chains. Observably, manufacturers are investing earlier in supplier qualification audits and digital traceability platforms not only to meet customs demands but also to preempt downstream customer requests for full material declarations. It is more appropriate to understand this as a structural tightening of technical due diligence — one that extends beyond regulatory minimums into commercial risk mitigation.
Strategic Implications for Global Electronics Trade
This development underscores how single-commodity tariff decisions can cascade across high-value electronics sectors — even when copper constitutes a relatively small weight fraction of finished products. The convergence of trade policy, environmental regulation, and supply chain transparency means that responsiveness to material-level compliance is no longer optional but foundational to market access. A measured, evidence-based approach — grounded in verifiable documentation and proactive supplier engagement — remains the most resilient path forward.
Source Attribution and Ongoing Monitoring
This article was generated exclusively from the user-provided title, event timing note (‘not specified’), and factual summary. Specific official source links were not provided in the input and should be verified continuously. Stakeholders are advised to monitor upcoming U.S. International Trade Commission (USITC) determinations, updates to CBP enforcement guidance on origin tracing, revisions to EU SCIP database reporting thresholds for copper alloys, and industry feedback on REACH dossier validation practices for metal composites.
Recommended News
 Sep 11, 2026Hotel Security Protocols: A Compliance Checklist for Protecting Guests and StaffSecurity protocols for hospitality: use this practical hotel compliance checklist to protect guests, staff, data, access points, and emergency operations.
 Sep 10, 2026How to Evaluate Resort Slide System Suppliers for Safety, Capacity, and Project SupportResort slide systems supplier evaluation guide: compare safety evidence, real capacity, durable materials, and project support for confident resort investments.
 Sep 09, 2026Sustainable Building Materials Pricing: How Buyers Compare Cost, Life Cycle, and RiskSustainable building materials pricing explained: compare installed cost, life-cycle value, carbon evidence, and supply-chain risk for smarter procurement decisions.
 Sep 08, 2026How to Build Stable Interoperability Across Hotel Guestroom SystemsHospitality system interoperability stable: learn how hotels can align room states, command priorities, local fallback, and testing for reliable guestroom operations.
 Sep 07, 2026How to Plan Outdoor Kinetic Art Installations for Parks, Resorts, and Public SpacesOutdoor kinetic art planning guide for parks, resorts, and public spaces—explore safety, engineering, materials, lifecycle costs, and maintenance for lasting visitor impact.
 Sep 07, 2026Amusement Equipment Testing for Family Entertainment Centers: Key Safety ChecksAmusement equipment testing for family entertainment centers: discover essential safety checks for restraints, brakes, interlocks, structural wear, and daily operations.
 Sep 05, 2026What Engineering Performance Testing Should Cover During a Specification ReviewEngineering performance testing for specification review: learn how to verify structural strength, durability, safety, sustainability, and system reliability before costly project decisions.
 Sep 04, 2026Planning Recreational Cable Transport Networks for Resorts and Mountain ParksExplore recreational cable transport networks for resorts and mountain parks, with expert planning insights on capacity, terrain, safety, station design, and long-term performance.
 Sep 03, 2026How to Plan Theme Park Infrastructure for Mixed-Use DevelopmentsTheme park infrastructure for mixed use developments: plan resilient utilities, circulation, attractions, hospitality, and digital systems for scalable destinations.
 Sep 02, 2026Mountain Slide Systems Pricing: Key Cost Factors for Resort ProjectsMountain slide systems pricing explained: explore key cost drivers for resort projects, from terrain and logistics to safety compliance, installation, and lifecycle planning.
 Sep 01, 2026How to Use a Tourism Standards Database to Verify Safety and Compliance RequirementsTourism standards database guide: verify safety, compliance, evidence scope, test conditions, and jurisdiction requirements with confidence.
 Aug 31, 2026Material Performance Validation: Tests and Acceptance Criteria for Critical PartsMaterial performance validation: discover essential tests and acceptance criteria that help critical parts withstand loads, corrosion, fatigue, and real-world service conditions.
 Aug 30, 2026How to Choose Marine-Grade Camping Equipment for Saltwater and Coastal ConditionsMarine grade camping equipment guide for coastal trips: compare salt-resistant materials, wind-ready shelters, protected electronics, and maintenance tips for reliable adventures.
 Aug 29, 2026How to Assess Modular Building Suitability for Middle East Climate and Site ConditionsModular building assessment Middle East: evaluate heat, dust, corrosion, logistics, compliance, and lifecycle value for resilient site-ready projects.
 Aug 28, 2026What Do Standardized Performance Benchmarks Cost, and What Do Buyers Get?Standardized performance benchmarks price explained: compare costs, scope, and buyer deliverables to reduce procurement risk and make confident investment decisions.
 Aug 27, 2026Hospitality Supplier Comparison: A Procurement Framework for Quality, Cost, and ReliabilityHospitality supplier comparison: evaluate quality, total cost, compliance, and service reliability to reduce procurement risk and protect guest experience.
 Aug 26, 2026What Is a CMS and How Do You Choose One for a Growing Business Website?CMS explained for growing business websites: learn how to choose a CMS that supports SEO, workflows, integrations, and long-term scalability without costly rebuilds.
 Aug 25, 2026How to Evaluate Play Equipment Suppliers in North America for Safety and FitPlay equipment North America buyers: learn how to compare suppliers for safety, compliance, materials, installation support, and long-term fit before costly mistakes happen.
 Aug 24, 2026How to Build a Technical Procurement Content Workflow for Faster Vendor EvaluationTechnical procurement content workflow strategies for faster vendor evaluation: standardize intake, compare evidence clearly, surface risks early, and cut costly procurement delays.
 Aug 23, 2026What Makes Community Based Eco Resort Development Successful in Rural Destinations?Community based eco resort development succeeds when land fit, local participation, infrastructure, and operations align. Discover practical strategies for resilient, high-value rural eco resorts.
 Aug 22, 2026Poured Rubber Surfacing for Playgrounds: What to Evaluate Before Specifying ItPoured rubber surfacing for playgrounds looks ideal, but performance depends on drainage, substrate, testing, and maintenance. Learn what to evaluate before you specify it.
 Aug 21, 2026How Many Rooms Should an Eco Resort Have to Balance ROI and Guest Experience?Eco resort development room count directly shapes ROI, infrastructure efficiency, and guest privacy. Learn how to choose the right key range to protect margins and elevate the experience.
 Aug 20, 2026How to Evaluate Sustainable Concrete Alternatives for Low-Carbon Building ProjectsSustainable concrete alternatives: learn how to compare carbon data, structural performance, code compliance, and supply risk to choose low-carbon concrete solutions with confidence.
 Aug 19, 2026What Does a Marine Hospitality Consultant Do for Cruise and Yacht Projects?Marine hospitality consultant expertise helps cruise and yacht projects avoid costly design and procurement mistakes, improve guest experience, and build commercially viable onboard spaces.
Quarterly Executive Summaries Delivered Directly.
Join 50,000+ industry leaders who receive our proprietary market analysis and policy outlooks before they hit the public library.